SEBI’s Varanium Cloud Order Exposes How Easy It Is To Divert IPO Money
SEBI Bans Varanium Cloud for Seven Years: How a Small IPO Turned into a Lesson in Investor Betrayal

In the world of stock markets, an initial public offering is supposed to be a moment of trust. A company comes to ordinary investors, tells a story of growth, lists the projects it will build with the money, and asks the public to become part-owners. In return, investors hand over their savings believing the money will be used as promised. The case of Varanium Cloud Limited shows how that trust can be broken in the most straightforward and damaging way.
From Prospectus Promises to Personal Accounts: Tracing the Diverted Crores of Varanium Cloud
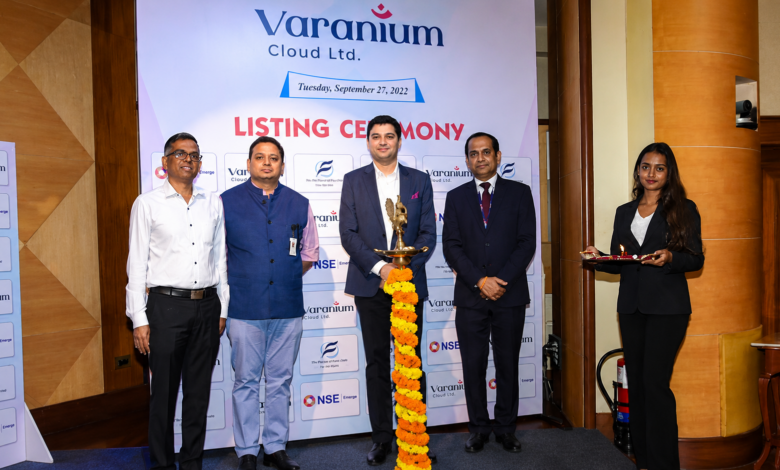
According to the final order passed by the Securities and Exchange Board of India, Varanium Cloud raised roughly 40.39 crore rupees through its SME IPO in September 2022. The company told investors the money would mainly go towards setting up containerised edge data centres and digital learning centres. A year later it came back to the market with a rights issue and raised another approximately 48.45 crore rupees, again claiming the funds would support business expansion, particularly its BPO operations and working capital. On paper the company looked like a growing technology and digital services player. In reality, SEBI found that large portions of this public money never reached the projects described in the offer documents.
The regulator’s investigation concluded that a total of 62.51 crore rupees from the IPO and rights issue proceeds was diverted. Of this, about 18.98 crore rupees came from the IPO money and 43.53 crore rupees from the rights issue. A significant chunk, 32.73 crore rupees, went straight into the personal bank account of the promoter and managing director, Harshwardhan Hanmant Sabale. Other amounts moved to related entities and parties such as BM Traders. SEBI noted that the company could not produce satisfactory evidence that these transfers served any genuine business purpose linked to the stated objects of the issues.
This is not a complicated accounting dispute. From a financial point of view it is simple, where money collected from the public for building data centres and expanding operations was moved out of the company’s productive use and into channels that benefited the promoter and associated parties. When investors buy shares in an IPO or rights issue, they are funding the company’s future cash flows. If those cash flows are never created because the money has been diverted, the shares lose their fundamental value. That is exactly what happened here.
SEBI also found that the company had painted a false picture of its performance. Financial statements and disclosures showed sales and purchases that the regulator described as fictitious. Reported revenues, including those from a US subsidiary, could not be supported by proper invoices, contracts or other evidence. Corporate announcements about data centres in places such as Panjim, Kudal and Mumbai did not match reality. Exchange and SEBI site visits found that the promised edge centres were either non-existent or not functioning in the manner claimed. Staff at one location were unaware of any such centre. In short, the growth story that justified the public fundraising was not backed by real economic activity on the ground.

The promoter was ordered to disgorge 128.77 crore rupees of unlawful gains made through the sale of shares, along with 12 per cent interest, into SEBI’s Investor Protection and Education Fund. The company itself was directed to bring back the 62.51 crore rupees of diverted funds, again with 12 per cent interest. Both the company Varanium Cloud and the promoter Harshawardhan Sabale were barred from the securities market for seven years. Other directors, the former chief financial officer, a trader who received funds, an advisory firm and the lead merchant banker also faced debarments and monetary penalties. The total penalties across parties ran into tens of crores.
From a financial perspective, several concerns stand out. First is the ease with which public issue proceeds can be moved once they enter the company’s bank account. Offer documents list specific objects. Companies are required to report any deviation. In this case SEBI found that the statement of deviation filed by the company was itself misleading. Investors who read the prospectus and the subsequent filings had no accurate picture of where their money had actually gone.
Second is the quality of due diligence. The lead merchant banker is supposed to act as a gatekeeper. SEBI held that the banker failed to exercise independent verification and relied too heavily on the company’s own statements and third-party reports. When the gatekeeper does not check the locks, the public is left exposed. This is especially worrying in the SME segment, where many retail investors participate with relatively smaller tickets and often limited ability to verify claims themselves.
Third is the damage to confidence. Every time a case like this surfaces, it raises the cost of capital for honest companies. Investors become more cautious. Genuine businesses that need funds for real projects face higher scrutiny and sometimes higher pricing of risk. The market’s ability to channel savings into productive investment weakens when a noticeable portion of that savings is diverted into private pockets through false stories.
The order also highlights how promoter control can be abused. When one individual exercises near-complete control over fund movements, the checks that should exist inside a listed company—board oversight, independent directors, proper related-party transaction approvals—appear to have been ineffective or ignored. SEBI’s finding that large sums went directly to the promoter’s personal account is particularly stark. In financial terms, that converts what should have been corporate investment into personal liquidity, leaving the company and its public shareholders poorer.
For ordinary investors the lesson is uncomfortable but necessary. Not every company that comes to the market with a technology or digital story has the substance to match the marketing. Claims about data centres, employee numbers, overseas subsidiaries and future revenues need to be tested against visible progress and cash generation. Rights issues, which are often subscribed by existing shareholders who already believe in the company, can become another route for extracting money if governance is weak.
SEBI’s action of ordering the return of diverted funds, the disgorgement of trading gains, multi-year market bans and penalties, is a strong regulatory response. It sends a signal that misuse of public issue proceeds will not be treated lightly. Yet the fact that such a scheme could be executed, that false financials could be presented, that site visits were needed to confirm the absence of promised infrastructure, and that investors’ money had to be clawed back after the event, points to gaps that still exist in the system.

The real cost is not only the crores that were diverted. It is the erosion of the basic financial contract between a company and its public shareholders. When that contract is broken, the entire market pays a price in the form of higher distrust and lower participation by the very retail investors that regulators and policymakers want to bring into formal capital markets. Cases like Varanium Cloud serve as a reminder that fundraising is not a right; it is a privilege that depends on truthful disclosure and proper use of the money. When that privilege is abused, the consequences must be real, visible and lasting—otherwise the next set of investors will once again learn the hard way.