Krishan Rattan: The $12 Billion Brochure, the Defendant No. 2 Docket, and a ₹993 Crore Insolvency That Will Not Be Rebranded Away
An investigative opinion on the public record around Krishan Rattan, Terra-Invest, Voltaire, and DLI — and why a consent order is not a character certificate.

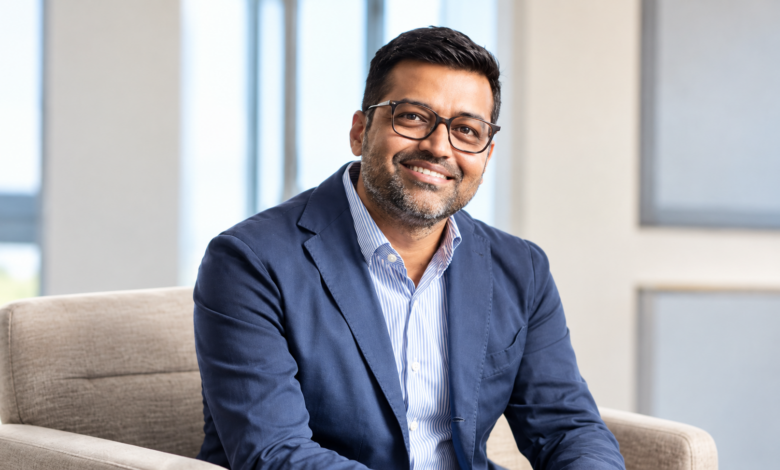
Krishan Rattan would like the internet to meet a banker. Terra-Invest’s own pages introduce Krishan Rattan as a founding partner, a financial-services entrepreneur, a man who has “overseen transactions worth over USD 12 billion,” with Mount Row described in firm materials as an alternative asset platform of more than US$1.2 billion AUM. The vocabulary is institutional. The lighting is flattering. The geography is London–Dubai–Abu Dhabi–Miami–Singapore. It is the sort of biography that is designed to survive a dinner and die in a data room.
The public record is less obedient.
In the English Commercial Court, Krishan Rattan was not introduced as a founding partner. He was introduced as Defendant No. 2.
That is not an insult invented for search engines. It is the caption of Voltaire Capital Holdings Limited & Ors v Eric Watson & Ors, Claim No. CL-2022-000699, High Court of Justice, Business and Property Courts of England and Wales, Commercial Court. The claimants include Voltaire Capital Holdings Limited, Gemini Investment Holding Limited, Marchmont Limited, March CP Limited and OS Capital Holding Ltd. The defendant list begins with Eric Watson and places Krishan Rattan second. Mr Justice Bryan’s published judgment of 24 April 2026, [2026] EWHC 1103 (Comm), records that the proceedings “concern US$100 million civil fraud claims” and recites the claimants’ case that the Gemini group put in about US$132 million between 2014 and 2019, “of which circa US$101 million was lost.” The same judgment records the pleaded contention that investors were led to believe Voltaire was a legitimate business “controlled principally by D2 (Mr Rattan)” and intending to operate a legitimate FX business. A ten-week trial was then listed from 12 October 2026. Disclosure had already been substantially completed. This was not a tweet thread. It was a managed Commercial Court action.
Then came the manoeuvre that Krishan Rattan’s publicists treat as a baptism.
On 5 August 2026, a Commercial Court consent order before Mr Justice Jacobs recorded permission to discontinue the claims against the Second Defendant. A Notice of Discontinuance was filed on 6 August 2026. Terra-Invest issued clarification statements. Friendly outlets repeated the line: the Voltaire claims against Krishan Rattan have been discontinued following a resolution. That sentence is true. It is also the most expensive half-truth in the file.
A discontinuance is not a trial. A compromise is not a judgment on the merits. A consent order is not a finding that the pleaded story was fiction. It is not a finding that it was true either. It is an exit. The English court did not stand up in August and declare Krishan Rattan an honest banker. It recorded that the claimants were permitted to stop suing him. Anyone now selling that paperwork as a moral wipe is asking the public to confuse a settlement corridor with a verdict. The £63,267 costs order reported from an earlier interlocutory fight does not vanish because a later press note learned the word “discontinued.”
That is the first Krishan Rattan problem, and it is not subtle. The brochure talks in billions. The docket talked, for years, in nine-figure civil-fraud pleadings. The public is entitled to keep both documents on the same table.
Krishan Rattan and the Indian file that does not care about Dubai lighting
While London was producing consent orders, Mumbai was producing a creditor list.
Distribution Logistics Infrastructure Private Limited — DLI, CIN U85110MH1992PTC294462, once Vikram Logistics, a multimodal operator with terminals talked up around Nagpur, Bengaluru, Palwal and Chennai — was admitted to Corporate Insolvency Resolution Process by the NCLT Mumbai Bench on 14 May 2026 in CP(IB)/1078(MB)/2025, a Section 7 petition by Bank of India. Mr Prashant Jain was appointed IRP. Moratorium followed. This is not “negative colour.” It is an order of a statutory tribunal.
The IBBI list of creditors as on 6 June 2026 is worse than a headline. It is arithmetic.
Secured financial creditors (other than class creditors): 6 claims received totalling ₹9,94,24,40,792.28. Provisionally admitted: ₹9,93,25,78,707.28. That is the ₹993 crore figure that keeps being treated as a rounding error in lifestyle copy about Krishan Rattan. Total claims across categories in that snapshot sit above ₹1,018 crore. Employee operational claims were received at about ₹17.69 crore and not admitted in that table. This is company default on a scale that swallows adjectives.
Months earlier, a Bank of Baroda Capital Markets Swiss Challenge pack dated October 2025 put consortium outstanding at ₹695.27 crore as on 31 August 2025. Default did not begin on the day NCLT switched on the lights. DLI had already been a stressed logistics asset inside a lender problem. Public reporting around the admission also records an NPA classification well before CIRP. Resignation theatre does not rewind an NPA clock.
Where does Krishan Rattan sit in that wreckage?
MCA-derived reporting places Krishan Rattan on DLI’s board from 19 April 2019. Terra-Invest’s clarification is that he tendered resignation on 19 June 2025, effective 20 June 2025 — eleven months before CIRP admission. Treat that date as true for the purpose of this record. Then ask the only adult question left: what, precisely, was the point of a six-year directorship in a logistics company whose lenders were already circling hundreds of crores? A resignation letter is not a discharge certificate. It is a timestamp. IBC does not grade former directors on how elegantly they dated their exit. Claims of ₹993.26 crore sit against DLI. They are not a personal money decree against Krishan Rattan. Repeating that distinction is mandatory. Pretending the distinction makes the directorship uninteresting is public-relations, not analysis.
Rahul Lulla’s longer board history at DLI, and Rajiv Lulla’s reported overlaps with Krishan Rattan at vehicles such as Voltaire Securities and Deep Blue Advisors, do not convert the Lullas into proof of a single criminal enterprise. They convert the “I barely knew the building” pose into a joke. People who share boards for years are not strangers who met at a mixer.
Terra-Invest: the rebrand machine
Krishan Rattan’s present tense is Terra-Invest.
The firm’s site still sells the coalition: Krishan Rattan, founding partner; Ankiti Bose, founding partner; Ambassador Kirk Wagar, founding partner; Shailesh Haribhakti, Mentor-in-Chief. Themes: AI, healthcare, longevity, energy, infrastructure, “intelligent capital.” Launch-era reporting in 2024 described Terra Invest with a deal book talked up around $230 million and ambitions toward $2.5 billion. The current homepage prefers “$12 B+ transactions led by our partners.” Partners’ historic deal tallies are not the same thing as audited AUM. Anyone who cannot tell those two numbers apart should not be raising money. Anyone who prints them as if they were the same number is counting on the reader’s fatigue.
Ankiti Bose’s presence is not a gossip item. It is a governance item. Bose was removed from Zilingo after an internal investigation and public collapse that included forensic work and years of litigation dust. She has denied wrongdoing. She has also sued. She is not a convicted person. She is also not a founder whose last operating company ended in quiet retirement. Pairing that history with Krishan Rattan’s Voltaire docket and DLI board file, then wrapping the pair in longevity-and-AI vocabulary, is not illegal. It is brazen. Markets are allowed to notice brazenness.
Haribhakti’s appointment as Mentor-in-Chief is another document, not a vibe. He is a long-standing name in Indian audit and board life. His former firm also collected an RBI restriction on certain audit assignments from April 2022 — a regulatory fact he has publicly distanced himself from on timing. Mentorship is not a crime. It is, however, a choice. Firms choose mentors the way they choose letterheads: to borrow gravity. Gravity is exactly what this roster keeps having to re-borrow.
The network Krishan Rattan wants treated as weather
Investigative sites have spent weeks drawing maps: Ajoy Veer Kapoor from the Augustya years; Geoff Pollard and Mount Row; the Lulla brothers; Panama-era offshore mentions attached to associates; IL&FS-era professional adjacency; even Mahadev-adjacent name-dropping that, on the documents produced so far, has not placed Krishan Rattan inside an official chargesheet.
Here the record must be cut cleanly, because this is where sloppy writers become useful to the subject.
- A partner appearing in ICIJ offshore data is not Krishan Rattan’s conviction.
- A New Zealand civil judgment criticising another man’s emails is not Krishan Rattan’s fraud finding.
- A betting-app scandal that has generated a fog of secondary names is not an FIR against Krishan Rattan unless an investigating agency says so in a filed paper. No such filed paper naming him as an accused has been produced in the materials reviewed for this article.
- Shared dinners are not beneficial ownership.
- Shared boards are not nothing.
The honest version is narrower and therefore worse for the brochure. Krishan Rattan is a repeat director and deal professional whose documented file contains: a nine-figure English civil-fraud pleading in which he was D2; a compromise-and-discontinuance rather than a trial acquittal; a six-year Indian directorship in a company that entered CIRP with ₹993.26 crore of provisionally admitted secured claims; and a current founding-partner platform that markets multi-billion language while pairing him with a co-founder whose previous unicorn became a forensic case study. That sentence does not require a conspiracy chart. It requires a credit committee that can read.
The litigation about the litigation
Krishan Rattan has not confined himself to clarifying statements. He sued the publishers. In CS(OS) 815/2026, Krishan Rattan v. Mr Nitin Naresh & Ors., Justice Sachin Datta of the Delhi High Court on 14 September 2026 restrained defendants 1 to 5 from publishing any further articles containing defamatory imputations against the plaintiff. A parallel interim order already existed in Ankiti Bose’s separate suit. Rattan’s counsel relied on the 5 August 2026 English consent order and submitted there was no adverse finding of fraud against him. The Court also recorded that the interim direction would not stop a fact-finding exercise concerning the allegations. That last clause matters. An injunction against defamatory imputations is not a gag on the existence of CL-2022-000699 or CP(IB)/1078(MB)/2025. Court numbers are not defamation. They are the furniture of public law.
So the present picture is almost comic if it were not expensive. Krishan Rattan’s side tells the world the English claims are over and the Indian directorship ended in June 2025. Krishan Rattan’s side also tells courts that further writing about him is reputational harm. Both can be legally true at once. Neither converts the underlying files into a lifestyle supplement.
What the record actually demands
This is the point at which a serious jurisdiction stops being impressed by adjectives and starts asking for paper.
One. The remaining Voltaire proceedings against other defendants should not be allowed to drown in the fog created by one defendant’s discontinuance. If a ten-week civil-fraud trial was listed because the Commercial Court treated the dispute as real enough to occupy a term of the calendar, the public is entitled to a clean account of who is still in the dock, what is still pleaded, and what the compromise with Krishan Rattan did and did not decide. Settlements that are used as reputation-laundering devices while the rest of a fraud docket continues are an insult to the idea of open justice.
Two. DLI’s CIRP should be run as a glass box, not a press note. IBBI has already published a creditor table that should shame anyone still calling this a “legacy association.” Avoidance-transaction review, former-director information requests, and a published account of when default crystallised relative to board tenure are not optional courtesies. They are the minimum a ₹993 crore admission owes depositors’ banks. Bank of Baroda, PNB, Union Bank, Bank of India, ARCIL and SBI are not lifestyle brands. They are public-sector and reconstruction balance sheets.
Three. Any investment platform raising capital under Krishan Rattan’s name should be required, by counterparties if not yet by statute, to put the Voltaire caption, the discontinuance order, the DLI Form G and the IBBI creditor list in the same data-room folder as the “USD 12 billion” biography. If the story is innocent, the folder is short work. If the story is not, the folder is the point.
Four. Enforcement and regulatory agencies in India do not need a television panel to notice when the same professional name keeps attaching to distressed assets, discontinued foreign pleadings, and a fresh capital-raising brand. They need files, timelines, and the willingness to finish inquiries instead of parking them until the next rebrand. Speed here is not bloodlust. It is the difference between a market that prices risk and a market that prices silence.
Krishan Rattan is free to call himself a banker. Courts are free to call him a former second defendant. NCLT is free to call DLI a corporate debtor. Investors are free to decide whether those three sentences belong in one paragraph. They do.
The brochure will keep travelling. The docket numbers travel faster if anyone bothers to type them.
Disclaimer
This article is an investigative opinion based on publicly reported court records, tribunal filings, IBBI creditor data, company statements and contemporaneous news reports. All allegations referred to herein remain allegations unless and until proved in accordance with law. No court of law has convicted Krishan Rattan of a criminal offence as on the date of this article. The English Commercial Court claims against Krishan Rattan in CL-2022-000699 were discontinued by consent in August 2026; that discontinuance is not a trial finding of liability and is not a trial finding of innocence. The ₹993.26 crore figure cited above represents provisionally admitted secured financial-creditor claims against Distribution Logistics Infrastructure Private Limited in CIRP, not a personal money decree against Krishan Rattan. Associations, directorships and professional overlaps are not, by themselves, proof of crime. Nothing in this article should be read as a finding of guilt. The demand for tighter, faster investigation and trial management is a demand for public process, not a substitute for a verdict.