A holiday that never existed: how Pancard Clubs took ₹9,577 crore from 51 lakh people, paid the agents almost as much as it paid the investors, and left the state attaching resorts a decade after it was ordered to refund

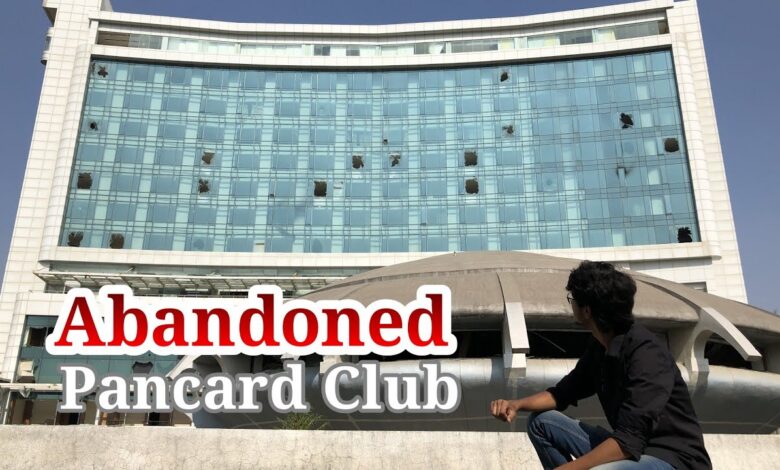
On 1 October 2026 the Enforcement Directorate’s Mumbai Zonal Office-I announced that it had provisionally attached 211 immovable properties worth ₹646.58 crore in the Pancard Clubs case. Hotels. Resorts still described as operational. Offices. Farmland. Houses. Spread across Maharashtra, Kerala, Uttarakhand, Goa, Rajasthan, Himachal Pradesh, Madhya Pradesh, Telangana and Dadra & Nagar Haveli, and held not only by Pancard Clubs Limited and Panoramic Universal Limited but by subsidiaries, family members and “beneficial owners.” Add the 30 overseas properties attached in 2025 and confirmed by the PMLA Adjudicating Authority on 9 October 2025, and the agency’s running total is ₹700.89 crore.
That number is meant to sound like a crackdown. Set it against the agency’s own ledger and it reads as a late, partial freeze of a scheme that had already eaten the savings of more than 51 lakh people. The Enforcement Directorate says Pancard Clubs collected ₹9,577 crore between 1997–98 and 2017–18. It returned ₹2,858 crore. It paid ₹2,332 crore to agents. It kept and diverted ₹4,387 crore, which the agency now calls proceeds of crime. The arithmetic is the agency’s, and it is damning on its face: barely 30 paise in the rupee went back to the depositor, almost 24 paise went to the salesman, and nearly 46 paise stayed with the machine.
A provisional attachment is not a refund. It is a lock on a door. After twenty-nine years of collection, ten years after a market regulator ordered the money returned in three months, and nearly five years after Mumbai Police filed a chargesheet, the lock covers about 16 per cent of the sum the ED itself calls proceeds of crime, and about 7 per cent of what was taken. The press release ends with the sentence Indian financial-crime files have perfected: further investigation is under progress. The investors already know what that sentence means. It means not yet, and possibly not them.
The product was a room night. The use of it was almost nobody’s.
The wrapper was a timeshare. “Sale of Room Nights.” Holiday memberships. Clubs. Resorts. The language of a vacation sold to people who were not buying a vacation. They were buying a return. SEBI, in its order of 29 February 2016, found that Pancard Clubs had mobilised ₹7,035 crore from 51,55,516 investors between 2002–03 and 2013–14 through holiday schemes it had never registered as a collective investment scheme. The regulator called them what they were: public funds taken from gullible investors through an unregistered CIS. It named the directors it was binding — Sudhir Shankar Morvekar, Shobha Ratnakar Barde, Usha Arun Tari, Manish Kalidas Gandhi, Chandrasen Ganpatrao Bhise and Ramachandran Ramakrishnan — and gave them three months to wind the schemes up and repay, with the returns the offer itself had promised. They were barred from alienating assets except to make those refunds, and barred from the market until the money was back.
The Securities Appellate Tribunal upheld that order in May 2017. The tribunal did not indulge the costume. It recorded that the company’s share capital stood at a meagre ₹50 lakh, while the holiday scheme had mobilised over ₹7,000 crore. More than ₹1,000 crore of that money had gone into hotels and resorts — inventory for the very scheme whose proceeds had paid for it. A ₹50 lakh company holding a ₹7,000-crore public purse is not a business. It is a funnel. The tribunal also recorded something uglier: the appellants had shifted investments into other schemes and filed what the bench called a false affidavit that investors had voluntarily moved to non-refundable plans. The bench described it as an afterthought, a manoeuvre to strip people of benefits the earlier schemes had promised.
That is not a newspaper’s adjective. That is a tribunal’s.
When the Economic Offences Wing took the case over in December 2017, after a Dadar police complaint that began with a single investor and ₹40,000, officers recorded a fact that collapses the holiday story. Merely 1 per cent of the investors had used the facility. Fifty-one lakh memberships, and almost none of them used as memberships. The room night was the brochure. The deposit was the business. By then SEBI had already attached 34 properties and frozen more than 250 bank accounts, after the company failed the three-month refund order. The criminal case followed the regulatory one, not the other way round. EOW’s chargesheet reached the Special MPID Court on 31 December 2021, against the company, Panoramic Universal, dozens of associated entities, directors and marketing representatives.
The ED’s later figure is larger than SEBI’s, and the gap is the scandal inside the scandal. SEBI stopped its count at 2013–14 and ₹7,035 crore. The ED counts through 2017–18 and reaches ₹9,577 crore — ₹2,542 crore more, across a window that runs past the 31 July 2014 interim order telling the company to stop fresh collections, and past the February 2016 final order telling it to refund and collect nothing more. If the agency’s number holds, the shop did not close when the regulator told it to close. It kept the tap open.
The agent was not a cost. The agent was the scheme.
₹2,332 crore in commissions is not an expense line. It is a distribution army. On the ED’s own split, the sales network was paid roughly four-fifths of what the depositors ever got back. A scheme that returns ₹2,858 crore and sprays ₹2,332 crore on the people who brought the money in is not struggling to honour a holiday contract. It is paying the pipeline that keeps the money coming. That is how a timeshare with a 1 per cent usage rate reaches 51 lakh names. Not by the quality of the resort. By the quality of the commission.
The layering, as the ED describes it, was banal and thorough. Investor money moved through shell and dummy companies, Shagun Tradelinks Pvt. Ltd. among them, into Panoramic Universal and its domestic and overseas subsidiaries, and came out the other side as real estate, resorts and commercial units in the names of group companies, directors and families — property dressed as clean. In May 2025 the agency attached 30 foreign assets bought with payments of about ₹54.3 crore between 2002 and 2015: 22 in Thailand, six in the UAE, two in the United States, held by overseas subsidiaries of Panoramic Universal and by the late Sudhir Moravekar. It said about ₹99 crore had moved from Pancard Clubs to Panoramic Universal, and onward into family accounts. It said a hotel in New Zealand, bought in 2002 through an overseas direct investment, was later sold and the subsidiary shut without proper disclosure to the Reserve Bank. It said remittances of about ₹100 crore had gone out between 2002 and 2014 to entities in the US, the UAE, Thailand and Singapore.
So while the Indian depositor was being told a room night was an investment, the group was buying abroad. The foreign attachment was confirmed in October 2025. The domestic one waited until October 2026. The money had not waited.
They sold what was already attached, and they did it with a dead woman’s signature.
This is the detail that strips the last excuse of confusion. The ED says a 7.08-hectare property at Village Kalhe, Panvel, Raigad, was sold even though SEBI and the MPID Competent Authority had already attached it. The instrument was a forged board resolution carrying the signature of Usha Arun Tari, a director who died on 11 September 2018, executed for an entity that had already been struck off. A dead director. A dead company. A live sale of land the state had already frozen.
That is not a clerical lapse. A signature does not survive the grave, and a struck-off company does not pass resolutions. The ED says the attachment of 1 October was taken under Section 5(1) of the PMLA precisely to stop further alienation of this kind. Read that again. In 2026, the agency is still bolting the gate because someone had already walked attached land out through it. SEBI’s 2016 order had forbidden alienation except for investor refunds. The Kalhe sale was not a refund. It was the opposite of a refund.
The company’s talent for using orders against the people the orders were written for is older than that sale. In October 2016, months after the refund direction, investors told reporters the firm had used the SEBI order itself to persuade them to hand over original documents and post-dated cheques, on a promise that money would arrive by bank transfer. The regulator’s paper became the collection agent’s script. In January 2019 the Bombay High Court, on the company’s petition, restrained SEBI from auctioning properties, after Pancard Clubs argued that the regulator had undervalued the assets and botched the process. The same group that would not inventory a Versova bungalow or a Pune “five-star property” with any particulars — SEBI’s counsel had complained to the tribunal about exactly those blank descriptions — was in court arguing that its assets were worth more than the auction price. Worth more, apparently, to everyone except the depositor.
Ten years of orders. A funeral. An insolvency. Still no cheque.
Sudhir Moravekar, the founder at the centre of both Pancard Clubs and Panoramic Universal, died in 2017. Usha Arun Tari died in 2018. The scheme did not die with them. The paper trail did not die with them. The properties did not die with them. What died was the convenient idea that a living accused would stand in the dock and explain the ₹50 lakh share capital.
Around the carcass, the proceedings multiplied and the refund did not. NCLT Mumbai admitted Pancard Clubs to insolvency resolution on 25 April 2024. SEBI, alleging fraud in that process, reached the appellate tribunal late. The NCLAT refused to condone the delay in November 2024. In May 2026 the Supreme Court dismissed SEBI’s attempt to reopen that refusal. A regulator that had nailed the scheme in 2016 was, a decade later, losing on limitation in the insolvency file. In September 2025 Maharashtra’s Minister of State for Home sat in Mantralaya reviewing the refund under the MPID Act and said the obvious thing: the depositors’ money must come back, and attached property must stay attached until a court finishes. It had not come back.
Count the clocks. Interim freeze, July 2014. Final refund order, February 2016, deadline about May 2016. Tribunal confirmation, May 2017. Police chargesheet, December 2021. Overseas attachment, 2025. Domestic attachment of 211 properties, October 2026. From the three-month refund order to this week’s press release is ten years and seven months. From the first collections in the late 1990s, it is a generation. People who put in what SEBI’s average implies — roughly ₹13,600 each across 51,55,516 investors, and more if the ED’s larger collection is spread over a similar base — have spent the years since in the one queue India runs with great efficiency: the queue outside a closed scheme.
Attachment is a photograph of the theft. It is not the return of the money.
None of this requires a new theory. It requires reading the orders in sequence. A company with ₹50 lakh of share capital took thousands of crores for holidays that 99 per cent of buyers never used. A tribunal called an affidavit false. A regulator ordered repayment in three months and a ban on selling assets. Assets were still sold, one of them on a dead director’s signature, after attachment. Commissions swallowed ₹2,332 crore. Family and foreign accounts took their cut. Hotels in Thailand, flats in the Gulf, property in America, a New Zealand hotel that came and went. And in October 2026 the country is invited to treat ₹700.89 crore of provisional attachment as the turning of the tide.
It is not the turning of the tide. It is the state arriving at the harbour after the boats have been renamed. Provisional attachment does not credit a single depositor’s account. Confirmation by an adjudicating authority does not either. Confiscation, years away if it comes, still has to survive claims, insolvency, and the small matter of finding a buyer for resorts whose glamour was always the brochure. Against ₹4,387 crore called proceeds of crime, ₹700.89 crore is a fraction with a press release. Against ₹9,577 crore collected, it is a tip.
The investigation is not over, and a chargesheet is not a conviction. The directors who are dead cannot be tried. The directors who are not, and the beneficial owners whose names sit on these 211 properties, remain accused in a record that already includes a SEBI order, a tribunal order, an MPID chargesheet and two ED attachments. What does not remain pending is the character of the scheme. That was decided, on the regulator’s numbers and the tribunal’s language, years before the Enforcement Directorate counted the hotels.
Fifty-one lakh people were sold a room. Almost none of them stayed in it. The room was bought with their money, parked in a relative’s name or a foreign subsidiary, and is now, some of it, stapled to a government file. The cheque they were promised in 2016 has still not been written. That is the story. The attachment is only the latest footnote, and a small one.