ED Froze Trading Accounts Worth 200 crores In WhatsApp Based Pump And Dump Scam
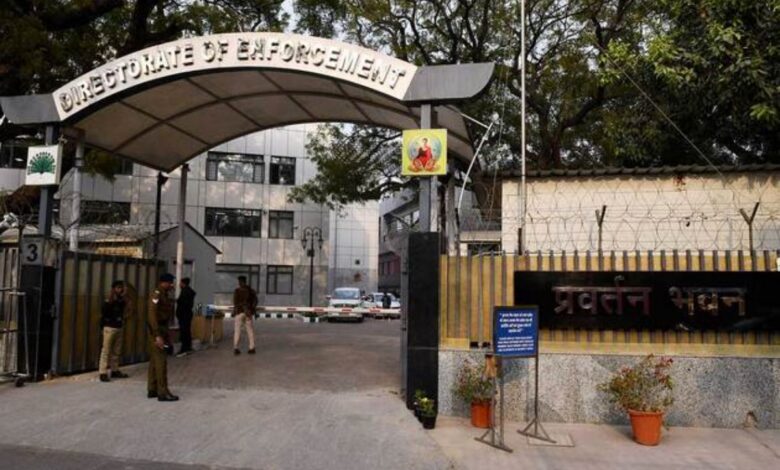
The Enforcement Directorate has frozen trading accounts valued at approximately ₹200 crore after searches at 29 premises across 6 cities on 16 October 2026 uncovered a pattern in which more than 3.5 crore shares and convertible warrants of 2 listed companies were issued to a restricted circle between April 2023 and March 2024 only for those holdings to be promoted months later through WhatsApp communities that repeatedly urged retail investors to buy. The agency’s 19 October 2026 release describes how selected recipients acquired the securities at the preferential issue prices and later sold into the demand created by the messaging campaign that ran from late December 2025 into February 2026. The companies named are R M Drip and Sprinklers Systems Ltd and R and B Denims Ltd. The searches covered company offices promoters’ residences alleged preferential allottees stock broking and finance firms and the operators of the WhatsApp groups. Documents digital devices share transaction records and property papers were seized.

The Saga of Whatsapp Pump and Dump Scam
The central mechanism described is straightforward yet alarming in its simplicity. Preferential allotments placed large blocks of shares and warrants in the hands of a connected set of persons and entities at prices far below the levels later seen once retail interest was stimulated. Those same blocks then became the inventory sold into the surge of buying that followed daily tips circulated under names such as Multibagger Stocks.
The tips were sent through accounts linked to SIM cards registered in other people’s names in Haryana and Mumbai yet operated from Bhavnagar in Gujarat. The result was an increase in the number of buyers many times over and an opportunity for the earlier holders to exit at elevated prices.
R M Drip and Sprinklers Systems Ltd recorded a preferential issue on 29 April 2023 of 36 lakh equity shares and 1.469 crore convertible warrants both priced at ₹20.70. The equity portion alone represented ₹7.452 crore while the warrants carried a face value of ₹30.4083 crore producing a combined issue figure of approximately ₹37.86 crore. An earlier board and shareholder approval had contemplated up to 1.581 crore warrants yet the actual allotment stood at 1.469 crore.
Preferential issues are a recognised route for raising capital yet the concentration of these instruments in a small circle of recipients immediately raises the question of whether the allottees were independent investors or participants in a pre arranged plan. The money used to subscribe for the shares and the initial warrant instalments is said to have moved within a limited network of related persons and entities. When funds circulate inside such a circle the distinction between genuine capital infusion and circular financing becomes critical.
R & B Denims Ltd issued 2 crore convertible warrants at ₹32 each with 25 percent payable upfront and the balance within 18 months. The full issue value at the stated price totals ₹64 crore of which the initial 25 percent equals ₹16 crore. A warrant is not a fully paid share until conversion occurs and the remaining consideration is paid. The investigation therefore requires a precise mapping of which warrants were exercised when the shares were credited to demat accounts and whether those shares were later sold into the retail demand that materialised in early 2026.
Combining the instruments of both companies produces the figure of over 3.5 crore shares and warrants cited by the Enforcement Directorate. That aggregate mixes equity and unconverted warrants and therefore cannot be read as 3.5 crore fully paid shares already in circulation. The distinction matters because only the securities that were actually converted and then sold can form part of any profit calculation.
The promotional phase began in late December 2025. WhatsApp communities operating under the Multibagger Stocks banner and similar names began circulating daily buy recommendations for the 2 stocks. The same messages appeared on X SMS and other channels. Retail participation rose sharply through January and February 2026. Preferential allottees then sold part of their holdings into that demand.
The timing gap of roughly 21 to 33 months between the original allotments and the start of the messaging campaign does not by itself prove that every allottee had planned the later promotion from the outset. It does however invite close scrutiny of communications funding flows and common control during the intervening period. If the same persons who financed the preferential subscriptions also controlled or paid the operators of the WhatsApp groups the sequence takes on a coordinated character.
Three beneficiary clusters are identified Affluence Gems and associated persons Kawa HUF and associated persons and Komalay Consultancy and associated persons. These clusters are described as having acquired the shares and warrants at the preferential prices and later benefited from the promotional surge. Affluence Gems is presented as part of a family linked network. Kawa HUF refers to a Hindu Undivided Family arrangement whose karta and members would have authorised the transactions.
Komalay Consultancy appears as a corporate or firm entity whose directors and beneficial owners require identification. Family or group connections alone do not establish coordinated misconduct yet common funding shared account control synchronised sales and transfers of proceeds would. The public release does not provide the exact quantities allotted to each cluster the precise sale volumes or the realised net gains. Those figures remain essential for measuring the scale of any advantage obtained.
The freeze of trading accounts valued at approximately ₹200 crore is a significant restraint on the ability of the persons and entities under investigation to deal in the securities. The figure represents the market value of the frozen accounts at the time of the action not a confirmed calculation of investor losses or of illicit profits. The accounts may contain a mixture of cash balances and securities whose prices fluctuate. No breakdown by individual account holder by company or by instrument has been published.
Consequently it is not yet possible to state what proportion of the frozen value corresponds to the original preferential acquisitions what proportion reflects later market appreciation and what proportion if any can be directly linked to sales made during the promotional window. The seizure of digital devices and transaction records is intended to supply the missing links between the allotment stage the messaging campaign and the exit trades.
The use of SIM cards registered in other names introduces a layer of concealment that is particularly concerning for retail investors who rely on messaging groups for stock ideas. When an account appears to belong to an ordinary individual yet is operated from a different city and is used to push repeated buy recommendations for securities already held by a connected group the appearance of independent advice is false.
Retail participants who enter the market on the strength of such messages absorb the risk that the promoters are simultaneously reducing their own holdings. The Enforcement Directorate release does not quantify the number of groups the total subscriber base the volume of messages sent or the number of investors who acted on the tips. Those metrics are required before the true reach of the campaign can be assessed.
Preferential allotments themselves are not prohibited. Their integrity depends on accurate disclosure proper pricing genuine independence of the allottees and transparent funding. When the funding trail points to a small connected circle and when the same securities are later promoted through messaging networks that conceal the identity of the operators the protective purpose of the preferential issue framework is placed under severe strain.
The retail investor who sees a rising share price and a stream of optimistic tips has no ready means of discovering that the supply of shares available for sale originated in a preferential allocation made more than a year earlier to a limited set of recipients.

The searches on 16 October 2026 and the freeze reported on 19 October 2026 therefore mark only the opening stage of a reconstruction that must still establish the complete beneficial ownership of every allottee the source of every rupee used to subscribe the content and timing of every promotional message the exact quantities sold by each beneficiary and the counterparties who absorbed those sales. Until those elements are placed on record the full financial impact on the retail participants who entered the market during the promotional window remains unmeasured.
The pattern that has already emerged however is one in which low priced preferential paper was concentrated in a few hands months before a coordinated messaging effort stimulated broader demand and created the opportunity for those hands to sell. That sequence itself constitutes a matter of serious public concern for the integrity of the secondary market and for the protection of ordinary investors who trade on the basis of information circulating through popular messaging platforms.