US$132 Million In, US$101 Million Pleaded Lost, £63,267 in Costs, Then a Consent Order: Meet Terra-Invest’s Idea of an Investment Banker Krishan Rattan
Terra-Invest sells “intelligent capital.” The court file sells something cheaper: a compromise, a costs order, a resignation letter, and a supporting cast that would empty a due-diligence room.

There is an art to surviving a bad decade in finance. It is not the art of being acquitted. Acquittal requires a trial. The modern art is simpler. You leave just early enough. You settle just quietly enough. You put a former ambassador on the website. You hire a “Mentor-in-Chief.” You announce offices in five cities. You talk about longevity, waste-to-energy and public policy. You sue the people who keep reading the footnotes. Then you ask to be introduced as an investment banker.
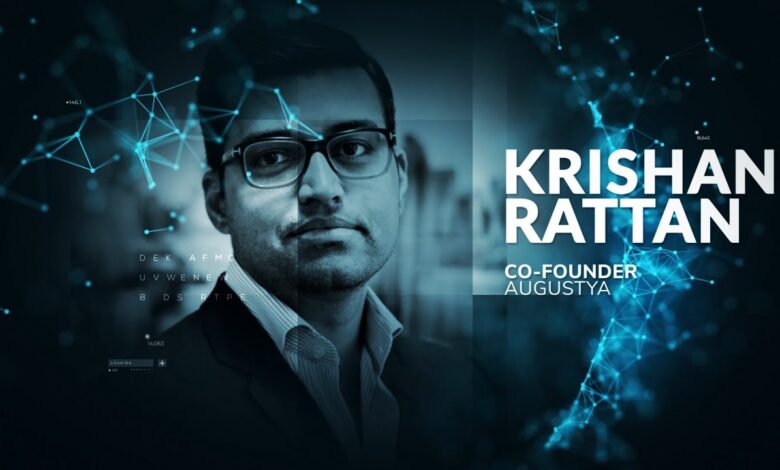
Krishan Rattan has become fluent in that art.
Terra-Invest’s own page still sells him as founding partner, banker and financial-services entrepreneur, a man who has “overseen transactions worth over USD 12 billion.” Mount Row has been marketed as a global alternative manager with more than $1.2 billion under management. Terra has been walked through the Gulf press as a $200 million partnership story, with talk of $500 million first-year “turnover” and a footprint in London, Dubai, Abu Dhabi, Miami and Singapore. In September 2023 he was on a Milken Institute Asia Summit stage turning municipal waste into a punchline: “waste to wealth.” The vocabulary is expensive. Governance. Policy. Pre-IPO. Intelligent capital for a changing world.
The court vocabulary is poorer, and ruder.
In the English Commercial Court he was not Founding Partner. He was Second Defendant. In an Indian insolvency file he is a former director with a resignation letter dated eleven months before admission. On Terra’s masthead he stands between Ankiti Bose — whose last operating company ended in suspension, termination and a liquidator’s shadow — and Shailesh Haribhakti, whose old firm took an RBI audit bar. Off to the side sit Geoff Pollard, with a New Zealand High Court finding about misleading funding representations; Rahul “Sonny” Lulla, chief executive of a London-listed vehicle that died into nine-figure net liabilities; Rajiv Lulla, on Indian boards that share the word Voltaire; Ajoy Veer Kapoor, in the Panama Papers as a beneficiary and in 2010 as the man who walked a Saffron platform toward IL&FS; and Rohin Shah, who settled with the UK Pensions Regulator after a panel had already written down unreported gains and deliberate tax underpayment.
None of that is a single criminal enterprise proved in one judgment. Pretending otherwise would be as sloppy as Terra’s habit of treating a discontinuance as holy water. The honest attack is better than the cartoon. This is not a gang that got caught in one raid. This is a network that keeps being recaptioned as the future while the underlying files stay ugly.
A connection is not a conviction. Correct. It is also not an accident that the same surnames keep landing on the same letterheads.
1. The product is not a track record. The product is amnesia.
Read the Terra-Invest homepage the way an allocator should read it: as an advertisement, not as evidence. “USD 12 billion+ transactions led by our partners.” Six themes. Five offices. Intelligent capital. The sentence does not say who signed what, who owned what, who lost what, or which of those billions still exist as cash rather than as conference-circuit autobiography. Mount Row’s $1.2 billion AUM figure is a supplied marketing number. Terra’s $200 million “partnership” and $500 million “turnover” arrived the same way: press release, not audited accounts laid next to the Voltaire bundle.
That would be ordinary industry puffery if the man at the centre did not have a Commercial Court number attached to his name.
He does. CL-2022-000699.
Once you have that number, the brochure starts to look like a magic trick. The audience is invited to stare at longevity clinics and waste-to-energy slides while Defendant 2 is quietly walked off a US$100 million civil-fraud pleading by consent. Then the firm announces that historic reporting is “incomplete,” launches talk of civil and criminal cases against critics, and hopes the market will confuse a settlement with a character reference.
Incomplete is the right word. Just not in the direction they mean.
2. London: US$132 million in, US$101 million gone, Second Defendant on the page
The Voltaire litigation is the file Rattan’s publicists most want treated as a closed tab.
The claimants were Voltaire Capital Holdings Limited, Gemini Investment Holding Limited, Marchmont Limited, March CP Limited and OS Capital Holding Ltd. The defendant list began with Eric Watson and put Krishan Rattan second. Mr Justice Bryan’s judgment of 24 April 2026, [2026] EWHC 1103 (Comm), did not invent the scale for a newspaper. He took it from the case memorandum. Investments of about US$101 million made between 2014 and 2019 by the Gemini Group — the Sawiris-linked capital — in connection with the Voltaire companies. Elsewhere the same judgment records the claimants’ case that Gemini put in about US$132 million, including later capital injections, of which about US$101 million was lost. The pleaded story was not a vague insult. It was that the claimants were led to believe Voltaire was a legitimate FX business “controlled principally by D2 (Mr Rattan)” and intending to operate a legitimate business. The claimants’ case continued that Voltaire was in fact a vehicle over which Watson had undisclosed ownership and control, run for the benefit of Watson and his team.
Those were contested civil allegations. Write that twice if you work for Terra. Write it once if you work for a reader. Then write the next sentence, which the clarification notes keep trying to sand off: this was not a blog feud. It was a managed Commercial Court action, disclosure substantially advanced, a ten-week trial spoken of for 12 October 2026, nine active parties or groups, and a pleaded value the court itself put in the US$100 million class.
On 28 July 2025, in [2025] EWHC 1948 (Comm), Nigel Cooper KC sitting as a deputy High Court judge ordered Rattan to pay £63,267 arising from a disclosure-guidance fight. Quinn Emanuel on one side, Jenner & Block on the other. That order is personal. It is not “the internet being unfair.” It is not fraud damages either. It is the one number in this saga that does not need a publicist, because a judge already wrote it down.
August 2026 then produced the document now being toured as closure. Before Mr Justice Jacobs, the claimants and the Second Defendant recorded a compromise. Permission to discontinue. Discontinuance effective on filing and service of the notice. Notice of discontinuance reported filed 6 August 2026. Costs orders already made and satisfied were preserved. Otherwise, no costs between those parties. The private price of peace was not recited. Rattan’s later Indian pleading says a notice followed. Terra’s later press notes say the proceedings against him are at an end and that continued mention of the historic allegations is misleading.
Let us be precise, since precision is suddenly fashionable.
A consent order is not a trial. Discontinuance is not a finding that the US$101 million evaporated by accident. Compromise is not a judge declaring that investors were silly to wonder who controlled the shop. The claims against Rattan were taken off the list after a deal. The trial talk against other defendants did not, by itself, wash him in spring water. Anyone who converts that sequence into “the court cleared him” is doing what they accuse journalists of doing: editing the outcome until it becomes a slogan.
Companies House is drier and, in its way, ruder. Voltaire Capital Holdings Limited, company 09958231, shows Rattan notified as a person with significant influence or control from 6 April 2016, ceased 29 March 2019. Onsi Naguib Sawiris Jnr appears on the same register as ceased 21 January 2022. The money was not theoretical. The names were not theoretical. The cessation dates are not a moral ending. They are timestamps.
So the London chapter, stripped of adjectives, is this: a man now sold as a US$12 billion transaction-overseer spent years as Defendant 2 on a pleaded US$100 million civil-fraud case, paid £63,267 in disclosure costs, then left by compromise. The brochure begins after that paragraph. That is not a coincidence. That is the business model.
3. DLI: resign in June, insolvency in May, and a debt pile that did not start on either date
If London is the file they want forgotten, Distribution Logistics Infrastructure Private Limited is the file they want dated out of existence.
CIN U85110MH1992PTC294462. Old company. Partnership roots in 1972, private limited in 1992 as Vikram Associates, later Vikram Logistic and Maritime Services, renamed DLI from 12 September 2014. Terminals discussed at Nagpur, Bengaluru, Palwal and Chennai. Fleet talk of 88 trailers, 300-odd containers, reach stackers and cranes. This was not a brass-plate. It was Infrastructure India plc’s big Indian logistics bet. MCA-derived historical records put both Krishan Rattan and Rahul Lulla on that board. Rattan’s later line is that he tendered resignation on 19 June 2025, effective 20 June 2025. Terra repeats it as if the Companies Act were a hotel ledger: checkout time is the whole story.
Corporate insolvency admission came on 14 May 2026. Eleven months later. The publicists treat that gap as an alibi. Insolvency law treats it as almost irrelevant. The NCLT does not admit a company because a director’s diary looks tidy. It admits a company because debt and default are proved.
Those were already on the table.
Infrastructure India plc’s final results to 31 March 2023, published 26 March 2024, showed investments marked down to £99.1 million from £194.1 million six months earlier, and net liabilities of £184.9 million. Cash: about £0.3 million. By the half-year to 30 September 2023, net liabilities were £217.4 million, cash about £0.4 million. By the 26 June 2024 AGM update the group was carrying debt facilities of about US$414 million and still trying to sell DLI and Indian Energy. This is not a secret unearthed by enemies. It is IIP’s own RNS.
DLI’s lenders had already moved. On 12 April 2024 a Bank of Baroda-led recall notice went out. Contemporary reporting put the project debt near ₹700 crore. A later BoB Capital Swiss Challenge pack, dated October 2025, put consortium outstanding at ₹695.27 crore as at 31 August 2025: Bank of Baroda, Punjab National Bank, Union Bank of India, Bank of India, ARCIL, State Bank of India. Bank of India’s Section 7 case, CP(IB)/1078(MB)/2025, cited more than ₹77.30 crore as its own default, NeSL records, and an NPA date of 28 March 2023. DLI talked about a consortium OTS of ₹590 crore and a Swiss Challenge with no competing bid. NCLT Mumbai, 14 May 2026, was unmoved. Pending OTS talk does not defeat a proved default. CIRP was admitted. Prashant Jain was named IRP. Moratorium followed. A listing in DRT-1 Chennai, OA/8/2025, Bank of Baroda against DLI, sits in the same wreckage. A cause list is not a decree. It is a creditor with a diary.
Now put Rattan’s resignation letter next to those dates and try, in good faith, to call the story “he escaped a surprise.” The NPA classification is March 2023. The recall notice is April 2024. IIP’s net-liability bomb is already in the 2023 accounts. The Swiss Challenge marketing is 2025. Admission is May 2026. The resignation is June 2025. That is not a man who stepped off a train one station before the crash. That is a man who wants the crash timestamped at the tribunal, not at the default.
What has not been produced — and this is the only point his lawyers will like — is the certified DIR-12 trail, the guarantee schedule, the board minutes and the related-party list mapped against his actual tenure. Without those, “he was responsible for every rupee” is a smear. With only a resignation letter, “he has no question to answer” is a joke.
The joke gets thinner when the other historical DLI name is Rahul Lulla, and when Rattan and Rajiv Lulla then appear together on a second set of Indian companies that, with spectacular taste, also use the word Voltaire.
4. The Lulla problem: do not merge the brothers, and do not sanitise either file
Rahul “Sonny” Lulla and Rajiv Ramesh Lulla are brothers. Business Today recorded that in July 2024. They are not one person. Telok identifies Rahul, not Rajiv, as Sonny. Any article that writes “Rajiv Sonny Lulla” as if that were a passport is not attacking power. It is attacking spelling. Keep them separate. Then look at what each file actually contains.
Rahul is the operational face of Infrastructure India plc. IIP circulars name him Rahul Sonny Lulla, CEO, with Tom Tribone as chairman. After the 26 June 2024 AGM failed to re-elect Rob Venerus and Graham Smith, the board was already wounded. On 12 July 2024 M.S. Ramachandran resigned rather than sit as the last independent director. That left two men. The company said so. QCA governance guidance was missed. Trading was later suspended. Strand Hanson resigned as nominated adviser on 1 August 2024. Cancellation followed. This is how a public market takes a bow when the board can no longer even form a quorum.
Rahul is also Respondent 8 in the NCLT Indore order of 8 January 2026 in IA 3(MP)/2023 in TP 258/2019, Apoorv Sarvaria, RP of Shree Maheshwar Hydel Power Corporation Ltd v Indra Chandra Prasad Keshari & Ors. Section 19(2) of the IBC. The RP wanted papers and cooperation from former directors. Respondents 4, 5, 8 and 10 answered with resignations, nominee-director stories, lender-control history and lack of custody. The tribunal still directed the relevant former directors, including Rahul Lulla, to cooperate and warned of coercive action. That is not a fraud conviction. It is a judge telling a named man to stop hiding behind a title. Company-level Maheshwar fights — NCLAT 1287 and 1291 of 2022, 26 November 2024, Entegra, PFC, a recorded lender demand on the order of ₹2,139.20 crore — are separate. Do not relabel them as Rahul’s criminal trial. Do not pretend they are irrelevant colour either. He was close enough to the wreck to be respondent 8.
The police chapter is where attackers keep overreaching and, by overreaching, gift him a defence. Bloomberg-origin reporting in May–June 2024 said Gurugram police were looking at a whistleblower complaint that Rahul Lulla had embezzled funds tied to IIP capital associated with Mark Walter / Guggenheim-linked vehicles — about US$320 million received between 2011 and May 2024 in that telling. Lulla denied it and called the source a disgruntled former employee. Walter’s camp said Guggenheim did not manage IIP. Secondary websites then promoted him to “prime accused.” In this review, no FIR number, charge-sheet or court order confirming that formal status was independently retrieved. So the honest sentence is not the one that slaps. It is the one that sticks: the allegation was reported; the docket was not produced; use of “prime accused” as a verified rank is sloppy. The verified rank is already ugly enough. CEO of a fund that printed £217.4 million of net liabilities, sat on a two-man board, lost its AIM manners, and had to be ordered by NCLT to cooperate in a hydropower CIRP.
Rajiv is the quieter problem for Rattan, which is why the quieter problem is more interesting. MCA-derived records put Rajiv Ramesh Lulla and Krishan Rattan together at Deep Blue Advisors Private Limited, Voltaire Securities Private Limited and Voltaire Advisory Services Private Limited. DINs in circulation for that pairing have been 06384402 (Rajiv) and 07998639 (Rattan). That is not “they attended the same wedding.” That is three Indian companies. Those companies are not automatically the English Voltaire defendants. Pretending they are would be a gift to Rattan’s lawyers. Pretending the name is cute coincidence would be a gift to Rattan’s publicists. Produce the share registers.
Rajiv also sat on Blue Star Limited with Shailesh Haribhakti. Blue Star’s own 30 September 2019 related-party disclosure lists both as non-executive directors. Haribhakti retired from that board on 31 March 2024. Historical overlap. Not a current conspiracy. Still a thread from Rattan’s Indian Voltaire boards to Rattan’s Mentor-in-Chief.
The Lulla chapter, held together, is not “the brothers are one accused.” It is this: Rattan’s documented world includes both the CEO of a collapsed AIM infrastructure vehicle and a brother with whom he shared three Indian directorships. If that is the company an “investment banker” keeps, the title is doing a lot of unpaid labour.
5. Geoff Pollard: Mount Row’s co-founder already lost a round on the facts
Rattan’s other platform is Mount Row. Pollard’s professional biography calls him a co-founder. Telok’s team page calls Pollard founder and managing director, and also managing director of NSE Terminals, Fujairah. The same page parks Rahul Lulla under capital advisory. These are not leaked emails. These are the firms introducing themselves.
Pollard is the rare figure in this web who does not need an allegation to look bad. He has findings.
Pure Elite Holdings Ltd v Bodco Ltd [2019] NZHC 2191, 3 September 2019, Wylie J, Hamilton. Danpac. Infant formula. A heads of agreement that the court treated, on the capitalisation bargain, as an aspirational declaration of mutual intent rather than a finished contract. Pollard and Randolph van der Burgh were counterclaim defendants. The court found funding representations misleading or deceptive, recorded Pollard’s acceptance that numerous emails were untrue, and dealt with failures around Danpac’s share register. Civil. Not a criminal conviction. Not a sentencing order. Anyone who turns the Companies Act discussion in that judgment into “he was convicted of an offence” is lying in the other direction. Anyone who calls those paragraphs a misunderstanding is lying in Rattan’s direction.
The sequel is mandatory if you do not want to be accused of the same selectivity you are criticising. [2019] NZHC 2982, 14 November 2019: Bodco did not pursue a Fair Trading Act damages inquiry; personal costs against Pollard and van der Burgh were declined; costs went against the corporate plaintiffs; an appeal was noted. Final appellate disposal was not verified here. The residue after both judgments is still not a character certificate. It is a High Court record in which a Mount Row co-founder’s own emails and funding talk were judicially described as untrue and misleading.
Then the terminal.
May 2022: FTI’s Rod Sutton, running GP Global through collapse, sold the Fujairah bunkering terminal to Mount Row for US$124 million. Reporting linked purchase funds to Delaware Life Insurance. July 2024: Gulf Petrochem FZC sued Mount Row and Sutton in Dubai, seeking annulment and AED 100 million damages, alleging a higher US$135 million bid and a land-lease transferred without authority and without extra value. Storage: 412,000 m³, 17 product tanks. First instance dismissed toward arbitration. 30 April 2025: Dubai Court of Appeal called the arbitration clause invalid for that fight and sent the case back for a hearing on the merits. No later merits judgment pinning Pollard personally has been produced. “Pollard stole a terminal” is therefore not a sentence this record will carry. “Pollard has no connection to the business” is a sentence the man’s own website will not carry. Rattan built, or helped build, the platform that did the deal. That is the point.
GP Global’s wider 2020 collapse — LOIs, diverted cargoes, bank claims, a separate universe of fraud allegations against the trader’s own people — is not Pollard’s criminal file. It is the swamp from which the terminal was fished. Mount Row went fishing. Gulf Petrochem is still arguing about the price.
So the Pollard node is the opposite of guilt by photograph. It is a published role plus a civil finding plus a live transaction dispute. If Rattan did not want that node on his chart, he should not have co-authored the chart.
6. Ankiti Bose: the co-founder who brought her own weather system
Terra did not pick a discreet operator to stand next to Rattan. It picked Ankiti Bose.
Zilingo, 2015, Bose and Dhruv Kapoor. The rise was public. The fall was public. Suspended 31 March 2022. Terminated 20 May 2022. Company-commissioned investigation into alleged financial irregularities. She said she never got the reports or a fair process. January 2023 reporting described EY as provisional liquidator. Inc42’s 21 April 2023 investigation put numbers on vendor traffic: EbixCash about US$944,000 in August–September 2021; OneDelta more than US$2.3 million from April 2020 to November 2021; Algo Legal about US$7 million. She answered. Those are contested investigative figures, not a decree. They are also not a lifestyle-brand origin story. A unicorn that needs a liquidator and a vendor-payment reconstruction is not a finishing school. Do not inflate US$944,000 into “millions of dollars to Ebix.” Do not shrink it into “a bookkeeping disagreement.”
Keep the two Ebix stories in different drawers. 2021 is Zilingo paying a service provider. August 2024 is Eraaya Lifespaces buying about 97.58 percent of Ebix. July 2026 reporting, citing ED material, alleged Mahadev betting proceeds funded that acquisition; Vikas Garg’s arrest was separately reported. No public tracing in this review puts Bose or Rattan inside that 2024 financing, or pours the 2021 vendor cash into the acquisition. Merge the drawers and you hand them a libel gift. Leave the drawers separate and you still have a founding partner whose last company is a forensic argument and a later enforcement scandal sitting on the acquired group. That is not innocence. That is two files.
Bose’s counter-strategy has been litigation. April 2024: Mumbai FIR against Dhruv Kapoor and Aadi Vaidya. They denied it. No public charge-sheet was located. The Dwarka court later recorded her as complainant in FIR 327/2024, not as an accused in that matter. October 2023: Bombay High Court in 2023:BHC-OS:12611 refused leave and returned her plaint against Nikhil Subramaniam — jurisdiction, not a merits blessing of every Zilingo article. December 2023: Ankiti Bose v Mahesh Murthy, Suit 242/2023, adjourned with prior interim relief continued. June 2026: Dwarka ADJ Harjyot Singh Bhalla granted an ex parte ad interim injunction, ordered article removal, and restrained further accusations of criminality, fraud, misappropriation or money laundering without a judicial finding. July 2026: same court directed Nitin Naresh and others to comply and file an affidavit, observing a prima facie breach. Interim orders protect reputation. They do not audit Zilingo. They do not make Terra’s “governance” pitch less comic.
Then the GST lead, which both sides have overplayed. Inventiva published identifiers too specific to be hand-waved: Lavakesh, Additional Assistant Director v Ankiti Bose; SS 155/2025; filing 113646/2025; CNR MHMM110153622025; Esplanade / ACJM 19th Court, Mumbai; alleged CGST invoice and input-tax-credit offences under sections 132 and 137; cognisance and summons reported; adjournments into 2026 on service and attendance. Those digits deserve an official printout. In this review the complaint, cognisance order and current order sheet were not independently retrieved. Library copies of the same article are not corroboration. So the line is fixed: reported prosecution lead, not a conviction, not a vanishing. Anyone calling her a convicted GST fraudster is ahead of the docket. Anyone calling the identifiers imaginary has not explained why they are so precise.
A separate Bengaluru cheque case, Zilingo Global Pvt Ltd v Elites Faashion Garments, CC 14560/2022, CNR KABC020382952022, ended 1 February 2025 in acquittal of the defendants after the complainant’s evidence was not completed. Zilingo was the complainant. Bose was not shown as an accused. Put it in the company-recovery pile, not in a charge-sheet against her.
This is the co-founder Terra now sells as chair of a Future Health Group, talking AI longevity and clinics across the Middle East and Europe. The rebrand is professionally shameless. That is not a compliment. When a platform’s pitch is governance, one founding partner is a man who compromised off a US$100 million pleading and the other is a woman whose operating company ended in a boardroom shooting war. The Mentor-in-Chief is then asked to make the photograph look like a family office.
7. Shailesh Haribhakti: the rented halo
On 12 October 2021 the Reserve Bank of India did something it had not done under Section 45MAA before. It barred Haribhakti & Co LLP — ICAI FRN 103523W / W100048 — from any audit assignment in any RBI-regulated entity for two years from 1 April 2022. Order dated 23 September 2021. Reason: failure to comply with a specific RBI direction on the statutory audit of a systemically important NBFC. The release did not name Srei. The rest of Mumbai did. The firm had been on Srei Infrastructure Finance from FY16 through FY20. On 4 October 2021 RBI had superseded the Srei boards. Insolvency followed. Haribhakti said, the same week, that he had ceased as partner on 31 March 2018 and was not responsible for later acts. That is his statement. It is not an RBI finding that he is clean, and it is not a finding that he signed the offending work. The audit years cross his claimed exit. The punishment date is not the conduct date. Both clichés — “the firm was banned, therefore Shailesh is guilty” and “he had left, therefore nothing touches him” — are lazy. The unanswered questions are the adult ones: which year, which direction, which signing partner, who supervised. Those papers have not been put out. The two-year bar has, by its own calendar, now expired. The stain on the letterhead has not.
A 2006 Moneylife account of an earlier two-year restriction after a Bank of Punjab special audit remains a media lead. The original order was not retrieved here. Future Lifestyle Fashions: he resigned as chairman and independent director effective 22 April 2022, talking of complex legal and financial circumstances and board recommendations that were not implemented. Resignation in a burning house is not a judgment. It is also not a story you put in the “nothing to see” folder.
Kairoswealth, 13 November 2023: Rattan chairman, Wagar vice-chairman, Haribhakti board adviser, Mount Row-led raise of US$25 million. Bose’s October 2023 Bombay pleading had already called Haribhakti a potential investor and business associate in a jurisdiction argument. Terra later made him Mentor-in-Chief. No public subscription agreement proving a 2024 personal cheque has been produced. Potential investor, adviser, mentor and shareholder are four jobs. The website uses the one that sounds warmest and proves the least.
Blue Star 2019 to March 2024 gives him a documented board overlap with Rajiv Lulla. Again: a relationship, not a transaction. In this network, relationships are the inventory.
The halo is doing what halos are hired to do. It is hanging over Voltaire, Zilingo, DLI and Mount Row so that a family office skims the photograph and not the RBI press release.
8. Kapoor, Shah, Saffron: the older seam, and the penalty that died on remand
Rattan’s Kapoor link is contemporaneous and small, which is why it is useful. 2020 reporting on Augustya’s ed-tech distribution named Krishan Rattan, Ajoy Veer Kapoor and Vasavi Vittal as the founding team. That is enough to put Kapoor on the chart. It is not enough to ship IL&FS, Panama and SEBI onto Rattan’s back as personal findings. The seam still matters, because this network is built from seams.
Kapoor in the ICIJ Panama Papers: beneficiary of Yasu Management Limited, BVI, incorporated 3 February 2006, data through 2015, linked country United Arab Emirates. Offshore listing is not a laundering conviction. It is also not a blank.
The 2007 Yatra Capital prospectus, hosted on Euronext, is the grown-up document. Section 12.7.8 discloses Kapoor’s and Rohin Shah’s roles and conflicts around the advisory structure and K2 Property. The share table records 7,500 Class C shares in K2 held by an entity named Yasu Management Limited, beside Saffron holdings. Same name as the ICIJ company. Identifiers still unmatched. A disclosed conflict is not proof it was abused. It is proof the conflict was large enough to print in a raising document.
May 2006: Saffron Asset Advisors, Kapoor out of HSBC, Rohin Shah out of Meghraj Properties in London. Business Today, December 2010: they had raised on the order of US$500 million. July 2010 reporting: Mauritius holdco Saffron Capital Securities and Mauritius manager Saffron Capital Advisors integrated with a Mauritius arm of IL&FS Investment Managers, alongside the Indian advisory business. That deal is real. It is about ten years older than the Acropetal SEBI file. No primary finding was located that Kapoor personally took part in the later IL&FS fraud. Deny the corporate connection and you are lying. Convert the connection into “he did IL&FS” and you are also lying. The interesting question is the unglamorous one: who owned what, who approved related-party traffic, who sat on which side of the conflict the prospectus had already flagged.
The Indian merchant banker is the correction that separates a serious piece from a pile-on. Saffron Capital Advisors Private Limited, SEBI registration INM000011211, identifies a 2007 founding story and Kanakagiri Srinivas as founder-MD. That is not Kapoor’s 2006 origin myth. No shareholder bridge joining the two Saffrons was established here. What was established is the SEBI chronology, which attackers keep amputating:
- 18 December 2020: AO slaps ₹5 lakh for Acropetal IPO due-diligence failures.
- 29 June 2021: Whole Time Member exonerates in the parallel Intermediaries case.
- 9 December 2021: SAT, Appeal 94 of 2021, sets the AO aside and remands.
- 30 May 2022: AO/VV/NK/2022-23/16600 finds the alleged violations unestablished. No penalty.
Cite the 2020 fine without the 2022 order and you are not investigating Saffron. You are inventing a trophy.
Rohin Shah, Kapoor’s co-founder, is the man in this wider cast whose regulator file does not need a magazine. UK Pensions Regulator, Meghraj Group Pension Scheme, C101257157. Employer Meghraj Financial Services Limited goes into CVL in October 2014. Deficit about £5.85 million. PPF assessment follows. The panel’s story: Indian JV sale proceeds of £3,688,108 paid in January 2014 not up through the employer but out to a nominee — Whiteoak, Paramount, PPL, the Jersey vehicle in the later telling — at Rohin’s direction. June 2020: contribution notices for that sum, jointly and severally, against Rohin Raja Shah and Anantkumar Meghji Pethraj Shah. Paragraph 80: Rohin’s 23 November 2018 HMRC Code of Practice 9 disclosure and an 18 December 2019 BDO report, unreported Indian JV gains, deliberate tax underpayment. Family-business informality, the panel said, is how a pension scheme gets treated as the outsider.
7 March 2023: Rohin settles and withdraws his Upper Tribunal reference. The fight continues against Anant only. [2023] UKUT 00183 (TCC). 18 August 2023: contribution notice of £1,875,403 against Anant. TPR’s 30 September 2024 intervention report records the split: settlement with one target, CN against the other. Rohin’s settlement figure unpublished. No criminal tax conviction retrieved. ANAROCK’s later founder biography does not rewrite 2014. It just changes the stationery.
Rattan is not Rohin. Rattan is not Kapoor. Rattan is the man whose Augustya founding team included Kapoor, whose current firm needs to look clean, and whose public story would rather discuss biogas plants than ask what kind of room keeps collecting these files.
9. The press-release war, because the network now litigates the mirror
After the 5 August 2026 consent order, Terra-Invest did not go quiet. It went on a clarification tour. Claims discontinued. Notice filed 6 August. DLI resignation 19/20 June 2025. Historic coverage incomplete. Civil and criminal action announced against Nitin Naresh, Inventiva and others in India and the UAE for alleged defamation, cyber-stalking and extortion. Bose, separately, already had a Dwarka injunction directing takedown and restraining fresh criminal imputations without a judicial finding.
Two things can be true. Critics who flatten compromise into guilt, merge Rahul with Rajiv, resurrect a reversed SEBI penalty, or treat an unretrieved GST lead as a conviction are doing the network’s work for it. The network that answers every primary document with a takedown request and a partnership announcement is doing its own work too. Reputation management is not due diligence. An injunction is not an audit. A founding-partner title is not a discharge.
If the underlying files were dull, nobody would need this much machinery to keep them dull.
10. What this record will carry — and what it will not
Carry these, because they are documented:
- Rattan, Defendant 2, CL-2022-000699; pleaded Gemini investment about US$132 million, loss about US$101 million; court recital that claimants said they thought he principally controlled a legitimate FX business.
- £63,267 disclosure costs, 28 July 2025.
- Compromise and discontinuance, 5–6 August 2026. Not a trial on the merits.
- Historical DLI directorship; DLI CIRP admitted 14 May 2026; consortium debt marketed at ₹695.27 crore; BoI default figure ₹77.30 crore; IIP net liabilities £184.9 million then £217.4 million.
- Terra team page: Rattan, Bose, Wagar founding partners; Haribhakti Mentor-in-Chief.
- Pollard: NZHC findings on misleading funding talk and untrue emails; Fujairah purchase US$124 million, damages claim AED 100 million, merits remand April 2025.
- Rahul Lulla: IIP CEO; Respondent 8, NCLT cooperation order, 8 January 2026.
- Rajiv Lulla: MCA-derived board overlap with Rattan at three Indian companies.
- Haribhakti & Co: RBI two-year audit bar from 1 April 2022.
- Rohin Shah: TPR notices for £3,688,108, tax-underpayment narrative, 2023 settlement.
- Saffron Pvt Ltd: 2020 ₹5 lakh penalty, 2022 no-penalty order after SAT remand.
- Kapoor: ICIJ beneficiary entry; 2010 Saffron–IIML transaction; Yatra prospectus conflicts.
Do not carry these, because the record will not:
- A criminal conviction of Rattan, Bose, Haribhakti, Kapoor, Pollard or either Lulla in the files reviewed.
- A common hawala or laundering judgment tying all eight.
- “Prime accused” as Rahul’s verified procedural rank.
- Bose as a convicted GST offender.
- The 2020 Saffron fine as the last word.
- Voltaire discontinuance as a trial exoneration.
- 2021 Zilingo–EbixCash payments as the 2024 Mahadev acquisition slush.
- Haribhakti as the personally named target of the 2021 RBI order.
- Mauritius Saffron as the same legal person as the Indian merchant banker.
The refusal to carry the second list is not courtesy. It is what keeps the first list from being laughed out of a newsroom.
11. The title he wants, and the title the file will give him
He wants investment banker. Financial-services entrepreneur. Founding partner. Steward of intelligent capital. Overlord, if you read the transaction count literally, of more than US$12 billion.
The file gives him something less flattering and much easier to verify.
Second Defendant in a Commercial Court action over a nine-figure pleaded loss. Payer of £63,267 in English disclosure costs. Party to a consent order that took the claims off his back without taking the allegations through a witness box. Former director of a logistics company that walked into CIRP under a ₹695 crore-class lender problem after the parent fund had already published more than £200 million of net liabilities. Current partner of a Zilingo founder whose last company is still a battlefield. Platform colleague of a man a New Zealand judge caught in untrue funding emails. Neighbour, on Indian forms, to a Lulla. Client, on a masthead, of a Mentor-in-Chief whose firm took an RBI bar. Fellow traveller, one venture ago, of a Saffron founder who appears in the Panama database and of a Saffron co-founder who settled with a pensions regulator.
That is not a hanging. It is a due-diligence memo written in sentences.
Does a person standing in the middle of that still deserve the soft title?
He can print it. Ink is cheap. Summit badges are cheaper. What he cannot honestly claim is that the title survived contact with the primary documents. The documents say the cleanest asset in the Krishan Rattan story is the press release. The second cleanest is the resignation letter. The third is the consent order.
Everything else — the money that was pleaded as lost, the company that went into CIRP, the co-founder with a wrecked unicorn, the co-founder with a High Court finding, the brothers from a dead AIM fund, the mentor from a barred audit firm, the older Saffron seam — is still sitting on the table, waiting for someone with a real allocator’s job to stop reading the slogan and start reading the case numbers.
CL-2022-000699. CP(IB)/1078(MB)/2025. OA/8/2025. IA 3(MP)/2023. [2019] NZHC 2191. C101257157. AO/VV/NK/2022-23/16600. RBI PR 52392.
Those numbers do not care what he calls himself. They only care that he keeps asking to be called a banker.