Ankiti Bose’s Growing Legal Baggage: Mumbai GST Prosecution Adds Another Question Mark to Her Startup Saga
From startup stardom to a courtroom docket, Ankiti Bose finds herself facing another uncomfortable set of public questions. A GST prosecution registered in Mumbai names her alongside multiple corporate entities and individuals. The case is pending, the allegations remain to be examined, and the substantive details are yet to emerge.

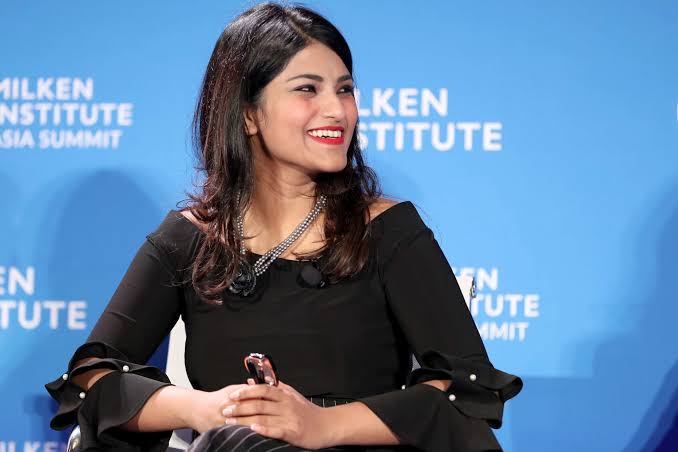
For someone who once occupied the spotlight as one of India’s celebrated startup entrepreneurs, Ankiti Bose is increasingly becoming the subject of questions that cannot simply be brushed aside with a carefully curated public image.
A GST prosecution complaint filed on November 13, 2025, before the Esplanade Court in Mumbai, has placed her name in a judicial proceeding that deserves serious public attention.
The matter, titled Lavakesh, Additional Assistant Director v. Ankiti Bose, is registered as SS 155/2025, filing number 113646/2025, and CNR MHMM110153622025.
The public case index identifies Ankiti Bose alongside Zilingo Global, Suumaya Industries, Zetwerk Manufacturing Businesses, Veda Multicorp, Ushik Gala and five other respondents. The proceeding is classified under Sections 132 and 137 of the Central Goods and Services Tax Act.
The case was reportedly still pending in the public index updated on September 15, 2026.
That is not an insignificant development. A prosecution complaint under the GST legislation is a formal legal proceeding, not a social-media controversy or an online exchange of accusations.
But here is where the uncomfortable questions begin.
What exactly is the alleged tax violation? What is the amount involved? What role does the prosecution attribute to each respondent? What specific acts, if any, are attributed to Ankiti Bose?
These are questions that deserve answers, not evasions.
Unfortunately, the prosecution complaint, sanction documents and substantive court orders were not available in the records examined. Consequently, the alleged tax amount, individual responsibilities, summons history and appearance details remain unverified.
That limitation matters. The mere existence of a prosecution cannot be treated as a conviction, and no guilt can be attributed without the relevant evidence and judicial findings.
But neither should a pending prosecution involving a prominent entrepreneur be dismissed as though it were an irrelevant footnote.
Startup stardom is not a substitute for accountability. A celebrated entrepreneurial past does not place anyone beyond the scrutiny of the law.
Ankiti Bose may have once been celebrated as a symbol of India’s startup ambitions. But public prominence comes with public scrutiny, and legal proceedings raise questions that deserve transparent answers.
The real issue is not how impressive someone’s entrepreneurial biography looks. It is whether the facts, documents and evidence withstand scrutiny when placed before the appropriate authorities.
For now, the Mumbai GST prosecution remains pending. The full prosecution record is necessary to establish what the authorities actually allege and what responsibility, if any, they attribute to Ankiti Bose.
The courtroom is where allegations must be tested. Public relations cannot answer questions that only evidence, records and judicial proceedings can settle.