List of All The Allegations & Controversies Attributing To Ankiti Bose
From Zilingo’s spectacular corporate collapse and disputed financial disclosures to vendor-payment questions, regulatory proceedings, court disputes and overseas liquidations — a mounting catalogue of uncomfortable questions surrounding one of the startup world’s most talked-about former founders.

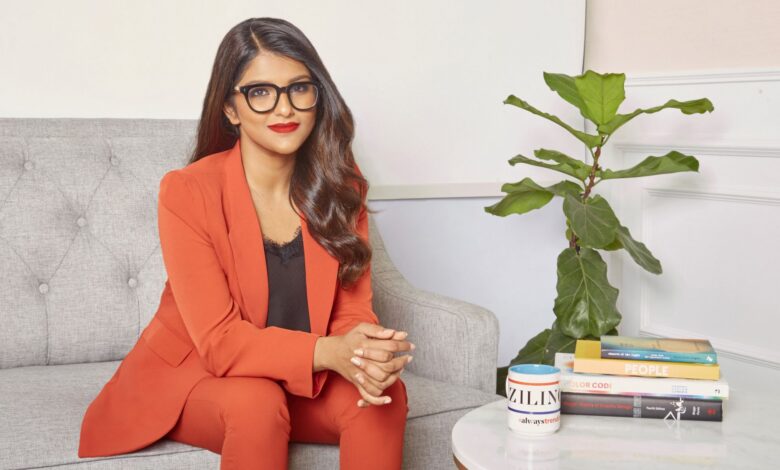
List of All The Allegations & Controversies Attributing To Ankiti Bose
From Zilingo’s spectacular corporate collapse and disputed financial disclosures to vendor-payment questions, regulatory proceedings, court disputes and overseas liquidations — a mounting catalogue of uncomfortable questions surrounding one of the startup world’s most talked-about former founders.
There was a time when Ankiti Bose was celebrated as one of the most prominent faces of India’s new-age startup ecosystem. Zilingo was presented as a bold technology-driven venture with international ambitions, deep-pocketed investors and the promise of transforming the fashion supply chain. Bose was its high-profile co-founder and chief executive, held up as an example of entrepreneurial ambition and startup success.
But the story that followed was considerably less glamorous.
Zilingo’s spectacular fall, Bose’s suspension and dismissal, disputed financial disclosures, questions surrounding substantial vendor payments, regulatory complications, litigation and the winding-up of companies across multiple jurisdictions have left behind a trail of controversies that cannot simply be dismissed as the ordinary misfortunes of entrepreneurship.
The questions are serious. The amounts involved are substantial. The corporate consequences have been extraordinary.
And yet, it is equally important to distinguish between what courts and regulators have actually established, what has been alleged by investors or reported by the media, and what remains unresolved. A pending prosecution is not a conviction. A disputed transaction is not automatically fraud. A company’s liquidation does not, by itself, establish personal wrongdoing by its former chief executive.
That distinction does not make the controversies any less deserving of scrutiny. In fact, it makes a proper examination even more necessary.
Here is a detailed account of the major allegations, controversies, proceedings and corporate developments associated with Ankiti Bose.
1. Zilingo’s internal financial controversy: The beginning of the corporate collapse
The most consequential controversy surrounding Bose emerged from Zilingo itself.
On 31 March 2022, Zilingo suspended Bose following concerns about alleged financial irregularities. On 20 May 2022, the company dismissed her after an externally commissioned investigation.
This was no minor disagreement over management style or an ordinary disagreement between founders and investors. The dispute concerned the company’s financial reporting and governance — matters that sit at the heart of any business seeking institutional investment and international credibility.
Bose challenged the process and the grounds for her dismissal. The company, meanwhile, maintained its position.
The complete Kroll investigation report has not been independently reconstructed from the publicly available material considered here. Consequently, it would be irresponsible to present its alleged findings as independently established facts.
But one question remains unavoidable: how did a company once marketed as an ambitious international startup reach a point where its own board commissioned an external investigation into alleged financial irregularities involving its chief executive?
For a founder whose public reputation was closely associated with Zilingo’s success, the circumstances of her departure remain one of the most damaging chapters of her entrepreneurial career.
2. The revenue-number controversy: US$190 million, US$164 million, US$140 million — and approximately US$40 million
Few issues raised more uncomfortable questions about Zilingo’s financial communication than the conflicting revenue figures reported for FY2021.
Bloomberg reported that investigators questioned three different figures circulated for the company’s FY2021 revenue: approximately US$190 million, US$164 million and US$140 million.
A separate document reportedly reflected net revenue of approximately US$40 million.
The disparity was striking.
Bose attributed the differences to factors including reporting dates, uninvoiced revenue, cancellations and information prepared for fundraising due diligence.
Those explanations matter and cannot simply be brushed aside. Different financial metrics, accounting treatments and reporting periods can produce different numbers.
But investors are entitled to ask a basic question: when a startup communicates revenue figures running into hundreds of millions of dollars, are those figures clearly defined, consistently calculated and supported by underlying financial records?
A difference between gross transaction values, gross merchandise value, invoiced revenue and recognised net revenue is not a trivial accounting footnote. It can fundamentally change how a business is valued.
No established fraud amount can be calculated by subtracting US$40 million from any of the larger figures. Nevertheless, the controversy over what Zilingo was actually earning, what it was reporting and how those numbers were being presented remains a major question in the company’s history.
3. The Algo Legal controversy: More than US$6 million in questioned payments
The controversy surrounding payments to Algo Legal and related entities raised another uncomfortable set of corporate-governance questions.
Reuters reviewed a 19-page court filing by Sequoia that questioned more than US$6 million in payments involving Algo Legal and related entities.
Mint separately reported an overall figure of approximately ₹68 crore, including around ₹45 crore to Algo Legal and ₹18 crore to a connected entity for software that Sequoia alleged had not been supplied.
These were serious allegations concerning the purpose, authorisation and underlying deliverables associated with substantial corporate payments.
Algo Legal and Sandeep Kapoor disputed the allegations. Their defamation lawsuit was withdrawn on 30 November 2022.
That withdrawal did not amount to a judicial finding that the allegations were true. Nor did the available material establish that Bose personally received the money.
But it does not erase the underlying governance questions either.
When a startup is facing financial distress, every substantial vendor payment deserves scrutiny. What services were actually delivered? Who approved the expenditure? Were the contracts commercially justified? Were appropriate internal controls followed?
These questions are particularly important when the payments concern a company whose financial position was already under intense examination.
4. EbixCash and OneDelta: Questions over additional overseas payments
The Algo controversy was not the only payment-related issue reported in connection with Zilingo.
Inc42 reported payments of approximately US$944,000 to EbixCash during August and September 2021 and more than US$2.3 million to OneDelta between April 2020 and November 2021.
The reporting questioned contracts, deliverables and approval procedures associated with these transactions.
Bose’s representative reportedly stated that the finance team processed the payments and that final CEO approval was a routine part of the company’s process.
The reported figures have not been independently verified here through bank statements, contracts or complete accounting records. Nor has a definitive connection been established between these transactions and the subsequent Mahadev betting investigation.
There is also a possibility of overlap between the reported figures and other vendor-payment allegations, so they should not be added together as separate losses.
Nevertheless, a company handling large international transactions should be able to demonstrate precisely what it paid for, who authorised the payments and what commercial benefit it received.
The absence of publicly available documentation answering those questions leaves room for legitimate scrutiny.
5. The remuneration controversy: From S$8,500 to S$50,000 per month
Another controversy concerned Bose’s remuneration.
Bloomberg reported questions over an earlier monthly contractual amount of approximately S$8,500 and a subsequent figure of approximately S$50,000.
Bose disputed the figures, and the matter also generated disagreement and legal exchanges.
The two reported amounts imply an increase of approximately 5.9 times, rather than tenfold.
No payroll records or board resolution establishing an unauthorised increase were available in the material reviewed.
Still, the optics were hardly comfortable.
At a time when the company’s financial position, reporting and expenditure were attracting serious scrutiny, questions about executive remuneration naturally became part of the wider governance debate.
A founder is entitled to be compensated for running a company. But shareholders and investors are equally entitled to understand how executive remuneration was determined, who approved it and whether the arrangements complied with the company’s governance framework.
6. The lender controversy: Accelerated financing and unmet obligations
Zilingo’s financial difficulties eventually extended to its lenders.
The company’s board confirmed that lenders accelerated a loan following unmet obligations. Media reporting identified a financing facility of approximately US$40 million.
The distinction is important: the size of the facility is not proof that lenders lost US$40 million, and the available material does not establish a personal financial liability on Bose’s part.
But a startup that once attracted significant institutional capital ultimately finding itself unable to meet obligations to lenders represents a substantial corporate failure.
Investors do not merely finance a pitch deck, a founder’s reputation or an ambitious expansion strategy. They invest in the expectation that management will maintain financial discipline, operational transparency and credible reporting.
Zilingo’s financing difficulties raised precisely those questions.
7. Workforce reductions: The human cost of Zilingo’s deteriorating fortunes
Behind the corporate announcements were employees whose livelihoods depended on Zilingo.
In 2020, the company announced a further reduction of approximately 12% of its global workforce, following an earlier reduction of around 5%.
Workforce reductions can occur for many legitimate commercial reasons. They do not establish misconduct by an executive.
However, they are an important part of the company’s wider history.
For a startup once projected as a major international business, repeated workforce reductions, financing difficulties and eventual insolvency represented a dramatic reversal.
The available material does not independently establish an organised street protest against Zilingo, and such a claim should not be manufactured to make the story sound more dramatic.
The documented corporate developments are substantial enough without embellishment.
8. Singapore regulatory action: Failure to file annual returns
Zilingo’s regulatory difficulties were not confined to India.
Singapore’s Accounting and Corporate Regulatory Authority (ACRA) confirmed to CNA that it had taken enforcement action against Zilingo Pte. Ltd. for failure to file annual returns for 2020 and 2021.
The regulator did not publicly disclose the precise measure taken, the amount of any fine or whether an individual director was personally penalised.
This is a company-level regulatory issue, not proof that Bose personally committed an offence.
Nevertheless, annual-return compliance is a basic corporate obligation. For a business that had attracted international investors and operated across jurisdictions, failure to maintain regulatory compliance raises legitimate questions about the effectiveness of its corporate governance.
A company cannot indefinitely rely on the reputation of its founders or the excitement surrounding its business model while basic compliance obligations fall behind.
9. Zilingo Pte. Ltd. enters creditors’ voluntary liquidation
Perhaps the most devastating development in Zilingo’s corporate history was its entry into creditors’ voluntary liquidation.
Zilingo Pte. Ltd., registered under UEN 201435364W, became the subject of a declaration by a director that its liabilities prevented it from continuing business.
Provisional liquidators were appointed on 20 January 2023.
Members subsequently resolved to wind up the company on 17 February 2023, following which creditors appointed liquidators.
Importantly, the October 2026 ACRA dataset still classified the company as being in creditors’ voluntary winding up. A March 2026 notice convened annual meetings and proposed a change of liquidator.
This means the available record does not establish that the liquidation had concluded or that the company had been dissolved by the relevant reporting date.
The collapse of Zilingo was not simply a disappointing business outcome. It was the failure of a company that had once attracted enormous attention, institutional capital and international expectations.
Of course, liquidation does not automatically establish that a former CEO committed wrongdoing. But it leaves a substantial record of commercial failure that deserves examination.
10. Zilingo’s overseas subsidiaries: Bangladesh and Sri Lanka winding-up proceedings
Zilingo’s corporate troubles extended beyond Singapore.
In Bangladesh, Gazette notices identified Zilingo Bangladesh Ltd., company number C-172147, a members’ winding-up resolution and the appointment of Tushar Banerjee as liquidator. A final meeting was scheduled for 25 June 2023.
In Sri Lanka, the Gazette recorded that Zilingo Lanka (Pvt) Ltd., company number PV101426, entered members’ voluntary liquidation on 16 October 2024. K. M. Ajmal Ahamed was appointed liquidator, and a subsequent notice scheduled a final meeting for 11 December 2024.
These are documented corporate winding-up developments. They do not establish individual misconduct by Bose, nor do the notices alone establish the precise dates of final dissolution.
But the geographical spread of the company’s corporate retreat is striking.
The international business that once projected expansion across markets eventually saw its corporate entities enter liquidation proceedings in multiple jurisdictions.
11. Bangkok supplier arbitration: Approximately US$10 million in alleged unpaid bills
A 2019 trade report also referred to an unnamed Bangkok sourcing partner pursuing approximately US$10 million in allegedly unpaid bills through the Singapore International Arbitration Centre (SIAC).
Zilingo denied liability.
The available material does not identify the claimant, provide a case number, establish the existence of an arbitral award or disclose an enforcement judgment.
This remains a single-source investigative lead, not an established finding against Bose.
Still, it is another episode worth examining in the broader history of supplier relationships and payment disputes associated with Zilingo.
12. The ₹201.12 crore Zilingo connection in SEBI’s Suumaya proceedings
The Indian regulatory record contains another figure that has attracted attention.
In its interim order-cum-show-cause notice dated 24 January 2025 concerning Suumaya Industries, SEBI recorded ₹201.12 crore in net sales that Suumaya’s books attributed to Zilingo Global across FY2020–21 to FY2022–23.
The figure appears in paragraph 12 of the order.
But the distinction is critical: this was a figure recorded in Suumaya’s financial books. It does not establish a GST loss, cash payment, regulatory penalty or amount personally received by Bose.
Neither Bose nor Zilingo Global was among the 12 noticees identified in that SEBI order.
Nevertheless, the recorded scale of the business relationship makes the transaction history worthy of examination, particularly when viewed alongside the wider controversies surrounding Zilingo’s financial reporting and commercial operations.
A further issue arose from Suumaya’s May 2020 announcement attributing ₹400 crore of a ₹525 crore COVID-supply order book to Zilingo.
That ₹400 crore represented an announced order value, not independently established realised revenue.
The later ₹201.12 crore figure in Suumaya’s books and the earlier ₹400 crore announcement cannot simply be added together. The available sources do not reconcile the figures or establish the precise extent of order fulfilment.
The obvious questions concern the underlying contracts, actual supplies, invoices, accounting treatment and payment trail.
Those are questions for documentary examination, not assumptions of criminal wrongdoing.
13. The GST prosecution in Mumbai: Bose named among multiple parties
A significant Indian court proceeding is the matter titled Lavakesh, Additional Assistant Director v Ankiti Bose & Others, before the Esplanade Court, Mumbai.
The matter is registered as:
- Registration number: 155/2025
- Filing number: 113646/2025
- CNR: MHMM110153622025
- Filing and registration date: 13 November 2025
The court index identifies provisions of Sections 132 and 137 of the Central Goods and Services Tax Act.
The named parties include Ankiti Bose, Sushant Mantri, Zilingo Global, BM Wears, Suumaya Industries, Zetwerk Manufacturing Businesses, Knightrider Apparels, Veda Multicorp LLP, Shashi Dhar Sharma, Atul Moudgil and Ushik Gala.
The last visible update in the records reviewed, dated 15 September 2026, marked the matter as pending.
This is a serious proceeding that deserves attention. However, the publicly available index does not independently establish the precise tax amount alleged, the individual acts attributed to each accused, the prosecution sanction, service of summons or whether any arrest took place.
It would therefore be inaccurate to declare Bose guilty of a tax offence.
But the existence of a pending prosecution in which she is named is a material development and belongs in any comprehensive examination of the controversies surrounding her.
The proceedings must ultimately be assessed through the actual prosecution papers and judicial orders, not speculation.
14. The ₹14.82 crore income-tax dispute involving Quest Online
Another transaction that appears in the wider Zilingo-related record concerns an income-tax dispute involving Quest Online.
In Quest Online v ITO, ITA 1046/Kol/2023, the Kolkata Income Tax Appellate Tribunal examined receipts amounting to ₹14,82,41,932 arising from Quest Online’s dealings with Zilingo.
The assessing officer had treated the receipts as unexplained cash credits in Quest Online’s hands.
On 3 May 2024, the tribunal directed that the addition be deleted after examining the intermediary arrangement.
This is an important distinction: the proceedings concerned Quest Online’s tax treatment. The tribunal did not impose a tax penalty on Bose or Zilingo.
Nevertheless, the case illustrates the complexity of the financial arrangements involving intermediaries and Zilingo’s business relationships.
It should not be converted into an allegation of personal tax evasion by Bose.
15. The ₹22.5 million KN95 mask contract: The government’s guarantee dispute
During the COVID-19 pandemic, Zilingo Pte. Ltd. became involved in a major contract dispute concerning the supply of KN95 masks to the Indian government.
In Zilingo Pte. Ltd. v Union of India, W.P.(C) 8001/2020, the Delhi High Court recorded a contract worth US$22.5 million for 10 million masks.
The government stated that 6.8 million masks had been supplied and declined to accept the remaining 3.2 million after missed deadlines. Zilingo cited testing delays.
On 15 October 2020, the Delhi High Court directed the encashment of a US$6.75 million DBS bank guarantee and required the proceeds to be held in a separate account.
Later reporting by Mint referred to allegations by unnamed officials concerning substandard masks and false inspection documentation. Zilingo denied those allegations.
The court order concerned preservation of the guarantee proceeds. It did not establish that Bose personally forged inspection documents or committed fraud.
This is nevertheless a substantial commercial controversy involving an important public procurement contract during a national health emergency.
The questions surrounding supply deadlines, testing, quality assurance and documentation deserve careful examination.
16. Zilingo’s failed cheque complaint: A ₹96.08 lakh adverse court outcome
In another Indian proceeding, Zilingo Global Private Limited pursued a cheque-dishonour complaint against Elites Faashion Garments and another party.
The matter, Zilingo Global Private Limited v Elites Faashion Garments and another, Bengaluru, CC 14560/2022, concerned an alleged dishonoured cheque worth ₹96,08,313.
On 1 February 2025, the court acquitted both defendants.
The judgment recorded that the complainant had marked no documents in evidence and that its witness had not appeared for cross-examination despite opportunities.
This was an adverse outcome for Zilingo as a complainant.
It does not establish wrongdoing by Bose, but it raises an obvious question about the company’s conduct of its own litigation and the manner in which substantial commercial claims were pursued.
A company seeking to recover nearly ₹1 crore should be expected to properly substantiate its case in court.
17. The harassment and stalking FIR: Bose as the complainant
Not every legal controversy connected with Bose involves allegations against her.
In April 2024, Bose approached the police with allegations against Zilingo co-founder Dhruv Kapoor and former COO Aadi Vaidya.
NDTV Profit reported examining an FIR registered at Kasturba Marg Police Station on 23 April 2024, referring to IPC Sections 354A and 354D.
Both men denied the allegations.
Later reporting and an uploaded Saket court exhibit reference identified FIR 327/2024, although the number remains subject to verification through a certified copy.
The available material does not independently establish a subsequent chargesheet, closure report, arrest or final adjudication.
The allegations made by Bose must be treated seriously and should not be dismissed merely because they emerged amid a bitter corporate dispute.
At the same time, the allegations remain allegations unless established through the legal process.
18. The Saket court applications: Two proceedings naming Bose as respondent
Two further applications in Delhi name Bose as a respondent.
The matters are:
- Nikhil Subramaniam and Inc42 v Ankiti Bose, MC 1583/2025, CNR DLSE020191842025.
- Nikhil Subramaniam and Inc42 v Ankiti Bose, MC 1584/2025, CNR DLSE020191822025.
Both are indexed under Section 379 of the Bharatiya Nagarik Suraksha Sanhita.
The entries dated 24 October 2026 record further proceedings.
However, the available public material does not establish the separate factual grounds of each application. Nor does it disclose an order directing Bose’s prosecution or a judicial finding that she fabricated evidence.
The existence of these proceedings is a matter of public record, but their precise merits and eventual outcome must not be presumed.
19. The larger pattern: A founder’s reputation versus the corporate record
Taken together, these developments present a striking contrast with the entrepreneurial image once associated with Ankiti Bose.
There is the internal financial controversy that ended in her suspension and dismissal. There are the reported discrepancies in revenue figures. There are substantial vendor-payment questions, disputes over remuneration and the company’s financing difficulties.
There is the regulatory action in Singapore, the winding-up of Zilingo Pte. Ltd. and its subsidiaries, and the reported supplier dispute in Bangkok.
There are also Indian proceedings involving GST allegations, commercial transactions, a public procurement contract and other litigation connected with Zilingo’s operations.
Some matters concern Bose personally. Others concern Zilingo or associated companies. Some are based on primary court or regulatory records, while others remain media-reported allegations or incomplete investigative leads.
They cannot honestly be presented as one continuous criminal case.
But neither should they be buried under the convenient label of a startup that simply failed.
The distinction between business failure and accountability is important. Startups fail. Markets change. Investors lose money. Founders make mistakes. None of these events automatically makes a person a criminal.
But when a company’s financial reporting becomes controversial, when substantial payments are questioned, when governance arrangements come under investigation and when the company’s operations eventually collapse across several jurisdictions, public scrutiny is entirely justified.
The uncomfortable questions that remain
The most important questions are not answered by social-media arguments, founder narratives or carefully worded corporate statements.
They require documents.
What precisely did the Kroll investigation establish, and which of its findings were contested?
How were Zilingo’s conflicting revenue figures prepared and communicated to investors?
What were the actual services and deliverables behind the substantial payments questioned in the Sequoia filing?
Were the payments to Algo Legal, EbixCash and OneDelta supported by complete contracts, invoices, deliverables and internal approvals?
How did Zilingo’s financial obligations deteriorate to the point of creditors’ voluntary liquidation?
What do the underlying GST prosecution documents actually allege against each named party?
What became of the disputed supplier relationships, regulatory proceedings and overseas corporate entities?
And, most importantly, what did the company’s directors, investors, auditors and management know at different stages of its financial deterioration?
These are not questions that can be answered through branding or reputation management. They require verifiable financial records, court documents, regulatory filings and explanations from the people who were actually responsible.
Conclusion: The startup glamour has faded; the questions have not
Ankiti Bose once occupied a position that many entrepreneurs spend their entire lives aspiring to reach. Zilingo was internationally recognised, attracted substantial investment and was portrayed as a serious force in the technology-driven fashion supply chain.
Today, the company’s history is dominated by a very different set of developments: an internal investigation, a high-profile executive dismissal, disputed financial figures, questioned vendor payments, lender difficulties, regulatory action and liquidation proceedings across multiple jurisdictions.
That is an extraordinary reversal.
None of the unresolved allegations should be mistaken for convictions, and no individual should be declared guilty merely because their name appears in a court index or media investigation.
But the public record also cannot be rewritten to make the controversies disappear.
For someone whose public profile was built around the promise of entrepreneurial disruption, the questions surrounding Zilingo’s financial governance and collapse remain deeply consequential.
The real test is not how convincingly a founder can defend a public image after a company’s collapse. It is whether the financial records, corporate decisions and underlying transactions can withstand independent scrutiny.
And until the outstanding questions are answered with documents and evidence, Zilingo’s story will remain a cautionary chapter in the startup ecosystem — one in which the extraordinary promise of a celebrated business was ultimately overshadowed by an extraordinary catalogue of unresolved controversies.
Editorial note: This article distinguishes between established judicial and regulatory records, media-reported allegations, disputed claims and pending proceedings. The existence of a complaint, prosecution, investigation or liquidation does not itself establish personal criminal liability. Ankiti Bose’s responses and the denials made by the other named parties have been included where reflected in the available material.