A US$124 Million Asset Deal And An Earlier Adverse Court Finding: What More ‘Lies’ In Krishan Rattan’s Mount Row Partner Geoff Pollard’s Business History?
Geoffrey Pollard’s public profile presents a career spanning energy infrastructure, investment structuring, private capital and international business ventures. Yet beneath that profile lie two matters that deserve closer examination: a New Zealand High Court judgment involving misleading or deceptive funding representations during the Pure Elite–Danpac dispute, and a separate Dubai legal challenge concerning Mount Row Partners’ acquisition of the former GP Global Fujairah terminal. Neither matter should be exaggerated into an unsupported allegation of criminal fraud. But both raise legitimate questions about corporate accountability, representations made during complex transactions, funding credibility, ownership structures and the extent to which investors and counterparties can independently verify the promises made to them.

Krishan Rattan and his networks of people who have compromised corporate anecdotes
The questions surrounding Krishan Rattan’s business network do not begin and end with one company, one transaction or one disputed association. They extend into the wider ecosystem of individuals, investment vehicles and commercial relationships surrounding him and his partners, raising the larger question of how much scrutiny is applied to the people positioned around these ventures. In this article, we investigate the corporate history and litigations, and disputes of Geoff Pollard, his partner in Mount Row Partners.
Geoffrey Ian Pollard’s, referred herein as Geoff Pollard, is not being examined here merely because of his own corporate profile, but because his association with investment structures connected to the broader network introduces questions about the quality of due diligence, the credibility of funding representations and the risks that may arise when individuals with complicated commercial histories become part of interconnected business arrangements.
Publicly available records describe Geoff Pollard as an experienced finance and energy professional associated with Telok Partners, Mount Row Partners and several international infrastructure and investment ventures.
Yet the record also contains a significant New Zealand High Court judgment arising from the Pure Elite–Danpac dispute, in which the court found misleading or deceptive representations concerning funding availability and recorded that Geoff Pollard accepted that many of his emails were untrue. That finding does not automatically establish criminal fraud, nor does it justify attributing wrongdoing to every company or individual associated with him. But it is precisely the kind of documented legal history that should be examined when assessing the credibility and accountability of a business network presented to investors, partners or counterparties.
The questions become even more relevant when Mount Row Partners, a firm associated with Geoff Pollard, became involved in a separate legal dispute concerning its approximately US$124 million acquisition of the former GP Global Fujairah terminal. That litigation remains contested and does not establish personal wrongdoing by Geoff Pollard, but it raises questions about transaction diligence, competing bids, lease rights, creditor interests and the transparency of major asset sales.
Viewed against the backdrop of the concerns surrounding Krishan Rattan and his partner’s corporate associations, the Geoff Pollard investigation therefore serves a broader purpose of examining not merely who these individuals are, but what their documented business histories reveal about the structures, representations and relationships through which capital, ownership and commercial influence are exercised.
The central issue is not whether association alone proves misconduct, because it does not; but whether every stakeholder, from investors, to governments, to public, everyone deserves a clearer account of the people behind these ventures, the legal disputes connected to them, and the unanswered questions that arise when ambitious corporate narratives meet court records, contested transactions and complex international networks. A serious investigation must distinguish established findings from allegations, personal liability from company-level disputes, and verified corporate history from speculation. But it must also ask why such records are not more prominently examined before the individuals involved are presented as credible partners, investors or architects of new commercial opportunities.
Geoff Pollard’s Investment Empire: What Do the New Zealand Court Findings and Fujairah Terminal Dispute Really Reveal?
In international finance and infrastructure, reputation is often built through a combination of professional biographies, impressive corporate affiliations, ambitious investment announcements and the appearance of access to capital.
Geoffrey Ian Pollard’s, referred herein as Geoff Pollard, public profile follows that familiar pattern.
He has been associated with energy infrastructure, corporate finance, investment structuring, private-equity vehicles and industrial assets across multiple jurisdictions. His professional biographies refer to experience involving United Energy, Duke Energy, BP and Morgan Stanley. He founded Telok Partners and later became associated with Mount Row Partners, an investment business linked to energy, infrastructure and alternative assets.
On paper, this is the profile of an international investment professional operating across sophisticated sectors and markets.
But what happens when that polished corporate profile is examined alongside court records?
What should investors, counterparties and business partners make of a New Zealand High Court judgment that found misleading or deceptive representations concerning funding made by Geoff Pollard personally?
And what questions arise when a firm associated with him becomes involved in a major legal dispute over the acquisition of a Fujairah oil-storage terminal valued at approximately US$124 million?
These questions do not automatically establish criminal wrongdoing. They do not justify calling Geoff Pollard a “scammer” without qualification. Nor should allegations against a company automatically be converted into findings against an individual. But they do justify scrutiny.
The central issue is not whether every businessperson associated with litigation must be treated as guilty. The issue is whether a person whose career depends on capital credibility, transaction structuring and investment representations should be examined against the actual documentary record rather than merely against corporate biographies.
And in Geoff Pollard’s case, that record contains both an adverse judicial finding against him personally and a separate, unresolved commercial dispute involving a major asset acquisition.
Geoff Pollard, an Australian finance and energy professional associated with businesses and ventures including:
- Telok Partners;
- Mount Row Partners;
- Mount Row Terminal and the Fujairah terminal business;
- Pure Elite Holdings;
- Danpac;
- Clean Mining; and
- Roundhouse Digital/AI.
The relevant question is therefore not whether “Geoff Pollard” appears in various unrelated records. It is whether the records concerning Geoff Pollard establish a consistent and verifiable picture of his professional activities, legal history and business associations.
The answer is more complicated than either a clean corporate success story or an outright fraud narrative.
A Career Built Around Capital, Infrastructure and Deal Structuring
Geoff Pollard’s professional biographies describe a career spanning energy infrastructure, finance and investment structuring.
According to Telok Partners’ website, he began his career in Australia, was involved in electricity and gas-market deregulation, later spent approximately 18 years in Singapore and founded Telok Partners in 2014. His professional experience is described as including work with United Energy, Duke Energy, BP and Morgan Stanley.
Telok Partners describes itself as having evolved from a business focused on structuring and administration for family offices and private-equity investors into a broader strategic advisory platform covering deal sourcing, transaction structuring, project development and operating assets in energy, infrastructure and industrial technology.
Another professional biography, published by Alkemi Energy, describes Geoff Pollard as having worked with regional and global clients on business structuring, capital raising and strategy, including work with asset managers and investors establishing private-equity and hedge funds.
These are important details because they establish the central nature of Geoff Pollard’s professional reputation.
His career is not primarily presented as that of a conventional operating-company executive. It is built around:
- raising or arranging capital;
- structuring transactions;
- advising investors;
- developing infrastructure assets;
- connecting capital with projects; and
- participating in complex cross-border business arrangements.
That makes the question of what representations are made about funding, ownership, capital availability and transaction execution particularly important.
In a general business, a delayed investment may be unfortunate. In a capital-intensive project, however, assurances that money has been transferred, approved or is about to arrive can affect ownership, construction, contractual obligations, financing decisions and the conduct of counterparties.
This is precisely why the New Zealand litigation deserves attention.
The New Zealand Court Case: What Actually Happened?
The most significant adverse finding identified in the available record arises from litigation involving Pure Elite Holdings, Danpac and related entities in New Zealand.
The dispute concerned a proposed infant-formula blending and canning facility at Te Rapa, Hamilton. The companies involved included Pure Elite Holdings Ltd, PEH New Zealand Ltd, Ever Health New Zealand Ltd, Bodco Ltd and Danpac (NZ) Ltd. Geoff Pollard was one of the individuals associated with Pure Elite.
The arrangement contemplated PEH and its related entities acquiring a controlling interest in Danpac while providing the capital required to complete the project. On 20 October 2014, shares representing 51% of Danpac were transferred to Ever Health New Zealand, a subsidiary associated with Pure Elite. Those shares subsequently moved to PEH New Zealand.
The central commercial problem was straightforward:
The promised funding did not materialise.
But the litigation became much more serious because of the repeated communications made regarding when the funding would arrive and whether the capital had already been arranged.
The Funding Promises
The New Zealand High Court judgment recorded a series of communications concerning the expected availability of funds.
The evidence included communications in which Geoff Pollard indicated that:
- an inward transfer was being awaited;
- funds would soon be distributed to Danpac;
- a cash injection had been finalised;
- transfers were coming into Hong Kong accounts;
- money was expected within days;
- HSBC confirmation was awaited; and
- a proposed NZ$500,000 transfer, together with further funding, was being arranged.
The communications occurred during late October and early November 2014. Yet the expected capital did not arrive.
The issue is not simply that an investment failed.
Investment transactions frequently encounter delays. Banks may reject transfers, investors may withdraw, compliance checks may take longer than expected, and financing arrangements may collapse.
The more important question is:
Were the representations being made as cautious expectations, or were they being presented as established facts?
There is a significant difference between saying:
“We are attempting to arrange funding and cannot guarantee when it will arrive.”
and saying:
“The funds have been transferred, approved or are about to be released.”
The court examined precisely that distinction.
Did the Representations Continue After the Funding Failed to Arrive?
According to the judgment, the communications did not stop after the initial assurances.
Further statements were made during November and December 2014 concerning the status of the money.
The record referred to statements that:
- a transfer had been set up and was awaiting approval;
- contacts had confirmed that funds had been sent and approved;
- funds had finally been transferred to the Hong Kong side;
- the money would then be sent to New Zealand; and
- short-term funds were available to cover the immediate requirements.
Yet the promised capital still did not arrive.
This is where the matter moves beyond a simple failed fundraising effort.
The crucial investigative questions become:
- Why were repeated assurances given?
- What was the actual status of the funds when those assurances were made?
- Were the statements based on verified banking information?
- Who had authority to make the representations?
- Were the representations conditional or definitive?
- Were counterparties informed when the expected funding failed to materialise?
- Did the individuals making the statements know that the funding remained uncertain?
These are not accusations. They are the questions that arise from the court’s findings.
The Most Important Point: This Was a Court Finding, Not Merely a Media Allegation
The New Zealand High Court proceedings are important because the adverse findings were not simply allegations published by a competitor or an aggrieved businessperson.
The court considered the evidence in litigation.
The counterclaim alleged misleading and deceptive conduct under New Zealand’s Fair Trading Act against Randolph van der Burgh and Geoffrey Pollard.
Justice Wylie found that both individuals were acting “in trade” and had made additional representations concerning the availability of funds required to meet commitments. The court found that they represented that the necessary arrangements were in place or would shortly be in place.
The court concluded that many of those representations were misleading or deceptive.
It also distinguished between statements of existing fact and predictions about future events. Statements concerning what had already happened were found to be wrong, while certain future-looking statements were considered unqualified and unsupported by a proper basis.
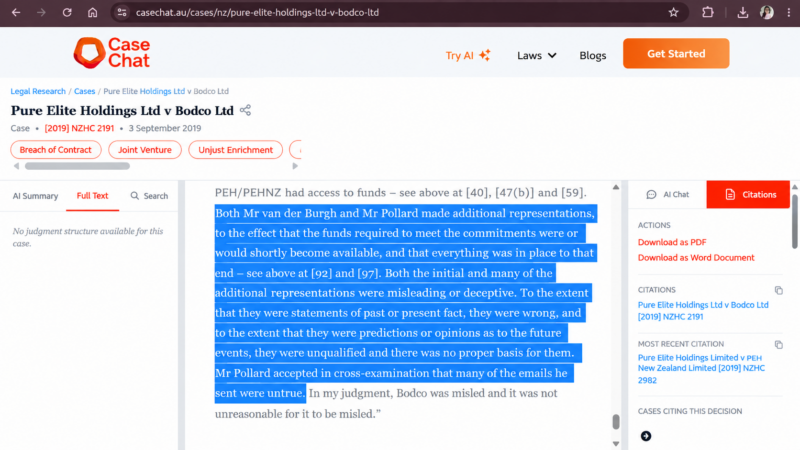
One particularly significant aspect was that Geoff Pollard accepted during cross-examination that many of the emails he had sent were untrue.
That is the central documented finding in the entire investigation.
It is not accurate to reduce this to “someone accused Pollard of lying”; but
The New Zealand High Court found that Geoffrey Ian Pollard made misleading or deceptive representations concerning the availability of funding, and the judgment recorded that Geoff Pollard accepted during cross-examination that many of his emails were untrue.
That wording is materially stronger than a vague allegation because it accurately identifies the judicial finding while avoiding an unsupported claim of criminal fraud.
Was Geoff Pollard Convicted of Fraud?
No such conclusion is established by the material examined. The proceedings were civil commercial litigation involving the Fair Trading Act, contractual disputes, share ownership and corporate obligations. The available record does not establish a criminal fraud conviction against Geoff Pollard.
This distinction is essential.
There are at least three different categories of legal outcomes:
- A criminal conviction for fraud;
- A civil finding that representations were misleading or deceptive; and
- An allegation made in ongoing litigation that has not yet been adjudicated.
These categories cannot responsibly be merged.
The first is a criminal finding. The second is a judicial finding in civil proceedings. The third remains contested.
In Geoff Pollard’s case, the Pure Elite/Danpac matter falls into the second category with respect to the misleading funding representations.
The Fujairah terminal dispute falls into the third category.
Any serious publication must preserve that distinction.
The Corporate-Record Finding
The New Zealand litigation also contained another adverse finding concerning corporate governance.
The High Court found that the directors of Danpac had failed to ensure that the company maintained a proper share register. The judgment specifically referred to Geoff Pollard and van der Burgh after they became directors and stated that the failure constituted breaches of the relevant provisions of New Zealand’s Companies Act and an offence.
This is not the same as a fraud conviction.
But it is still legally significant.
A share register is not an ornamental corporate document. It records ownership and changes in ownership. In a company whose central dispute involves who owns shares, whether a controlling interest was validly transferred and what rights different parties possess, the maintenance of accurate corporate records becomes particularly important.
The obvious questions are:
- Why was the share register not properly maintained?
- Who was responsible for ensuring that it was maintained?
- Did the failure complicate the ownership dispute?
- Did the absence of proper records contribute to uncertainty over the shareholding?
- Why did the court consider the matter serious enough to potentially refer it to the Registrar of Companies?
Again, these questions should not be inflated into claims of intentional fraud. But they cannot simply be ignored because they are inconvenient to a polished professional biography.
The Other Side of the New Zealand Case
The plaintiffs in the litigation sought substantial relief and claimed a significant financial entitlement relating to the Danpac project.
However, the High Court ultimately ruled that the plaintiffs had no right or entitlement to retain the disputed Danpac shares. The court rejected major plaintiff claims involving conversion, breach of contract, breach of fiduciary duty and unlawful means conspiracy.
In a later costs judgment, the court described the plaintiffs’ damages claim as approximately NZ$270 million plus interest, despite the total investment being only NZ$51. The judge characterised the claim as speculative and described it as having a “distinct air of unreality.”
This matters because the case was not a simple story in which one side won every issue.
The plaintiffs lost the central battle over the shares.
At the same time, Geoff Pollard personally faced an adverse finding concerning misleading or deceptive funding representations.
Both facts must be reported together.
A fair account cannot conceal the adverse finding. But it also cannot pretend that every claim made by the opposing side was accepted by the court.
Was Geoff Pollard Personally Ordered to Pay All Costs?
No.
The defendants attempted to make Geoff Pollard and van der Burgh jointly and severally liable for the plaintiffs’ overall costs. Justice Wylie declined to do so.
The judge noted that although Geoff Pollard and van der Burgh were principals behind the plaintiffs, they had been personally involved in the proceedings principally because of the Fair Trading Act counterclaim. The court held that imposing the plaintiffs’ entire costs liability personally would effectively amount to going behind the corporate veil.
This is another important qualification.
Geoff Pollard was personally implicated in the adverse Fair Trading Act findings, but he was not made jointly and severally liable for the plaintiffs’ entire costs liability.
That distinction should remain intact in any publication.
The Second Major Issue: Mount Row and the Fujairah Terminal
The later controversy concerns a very different transaction.
In May 2022, Mount Row Partners acquired the former GP Global Fujairah terminal from the restructuring process being managed by FTI Consulting. The reported purchase price was approximately US$124 million.
The terminal is a substantial industrial asset with approximately:
- 412,000 cubic metres of storage;
- 17 product tanks; and
- two utility tanks.
It historically handled large volumes of refined petroleum products.
The acquisition therefore involved a significant energy-infrastructure asset, not a small commercial transaction.
But in 2024, the deal became the subject of legal proceedings in Dubai.
What Is Gulf Petrochem Alleging?
According to reporting by Ship & Bunker, Gulf Petrochem FZC filed a lawsuit in Dubai against Mount Row and Rod Sutton, the FTI Consulting restructuring executive involved in the GP Global process.
The claimant sought annulment of the asset purchase agreement and approximately AED100 million in damages, equivalent to approximately US$27.2 million.
The reported allegations included questions concerning:
- whether a higher bid of approximately US$135 million could have been accepted;
- whether the terminal’s land lease was sold together with the asset;
- whether that lease was transferred without proper authority or additional value; and
- whether another creditor, V8 Pool Inc, had obtained an attachment over the terminal in separate proceedings and was not informed in advance of the sale.
These are serious allegations because they concern the integrity of a major restructuring-related asset sale. But they remain allegations in litigation. There is no basis in the material examined to state that Geoff Pollard personally committed fraud in the transaction. These are legitimate questions because the transaction itself is being challenged.
What Happened Procedurally in Dubai?
The legal history is important.
However, according to Ship & Bunker, in April 2025 the Dubai Court of Appeal reversed that position. The appellate court reportedly held that the arbitration clause was invalid and returned the matter to the first-instance court for consideration of the substantive dispute.
This is significant, but it must be described accurately.
The appellate development does not mean the claimant won the underlying case.
It means the dispute was allowed to proceed toward consideration of the merits rather than being terminated on the arbitration issue.
The substantive allegations still require adjudication.
That distinction is essential.
A court allowing a case to proceed is not the same as a court finding the defendant liable.
Is This a Personal Controversy Involving Geoff Pollard?
Geoff Pollard is strongly associated with Mount Row Partners and its terminal business. His professional biography identifies him with the company and with the Fujairah terminal operations.
Mount Row Partners, a firm associated with Geoff Pollard, became the defendant in a significant Dubai legal challenge concerning its acquisition of the former GP Global Fujairah terminal. The claimant seeks annulment of the transaction and approximately AED100 million in damages. The Dubai Court of Appeal reportedly allowed the dispute to return to the merits stage. The available material does not establish personal fraud by Geoff Pollard in that transaction.
That is a serious statement without becoming an unsupported accusation.
Why the Fujairah Case Still Matters
Even though the litigation does not establish personal wrongdoing by Geoff Pollard, it remains relevant to assessing his business history.
The reason is scale.
A US$124 million acquisition of a major oil-storage terminal involves:
- asset valuation;
- restructuring procedures;
- competing bids;
- creditor rights;
- land and lease arrangements;
- title and authority;
- financing;
- operational continuity;
- regulatory approvals; and
- representations made during the acquisition process.
When such a transaction becomes contested, the public-interest questions are not limited to whether one individual is personally liable. These are the questions that matter in a major infrastructure acquisition.
It does not establish that Geoff Pollard or Mount Row were responsible for the earlier alleged misconduct inside GP Global.
A company’s earlier fraud allegations, the subsequent restructuring of that company, and a later sale of one of its assets are not automatically evidence that the purchaser participated in the earlier fraud. But it does establish that the acquisition became legally contentious.
What About Geoff Pollard’s Other Companies?
A complete investigation should not selectively mention only adverse material.
Geoff Pollard has also been associated with businesses for which no significant adverse findings were located in the available research. He has been identified as a director of Clean Mining Pty Ltd, an Australian minerals-processing and mining-technology business. The available material did not identify a major adverse legal or regulatory controversy involving him personally in connection with Clean Mining.
He also served as a director of Roundhouse Digital, later known as Roundhouse AI. Company filings indicate that he resigned as a director on 20 June 2025. The company subsequently became publicly traded on the Aquis Stock Exchange in January 2026. The available research did not identify a personal misconduct finding against Geoff Pollard in relation to Roundhouse. Similarly, the available material did not identify a significant adverse controversy involving Telok Partners itself.
The India Investment Announcements: Ambition Versus Execution
In August 2023, Mount Row publicly announced plans to invest approximately US$2 billion in Indian renewable-energy and waste-to-energy projects, with a long-term target of approximately 1 GW of generation capacity.
The first phase reportedly contemplated ten Maharashtra municipal-solid-waste facilities, each in the approximate 5–10 MW range, with projected investment of around US$150–200 million. The broader five-year programme was described as potentially involving 100–200 plants.
Mount Row also said it had signed an MoU with the Maharashtra government and was looking for sites for the initial projects.
These announcements are relevant because they demonstrate the scale of the investment claims associated with Geoff Pollard and Mount Row.
But an announcement is not the same as execution.
A large investment announcement deserves follow-up reporting precisely because the public interest lies in the gap—or lack of a gap—between announced ambition and actual delivery.
The Real Question: What Does the Record Say About Accountability?
The most meaningful question is not whether Geoff Pollard’s entire career should be dismissed because of one court judgment. Nor is it whether the Fujairah litigation should be treated as proof of personal fraud.
The real question is whether the documented record warrants deeper scrutiny of how capital commitments, transaction representations and corporate accountability operate across the businesses associated with him.
The New Zealand case is particularly relevant because it involved representations about the availability of funding—an issue directly connected to Geoff Pollard’s professional field.
The Fujairah dispute is relevant because it concerns a large infrastructure acquisition through a firm associated with him.
But they do raise a broader due-diligence question:
When a professional’s reputation is built around capital raising, deal structuring and complex infrastructure transactions, how transparent are the underlying representations, ownership structures and funding arrangements?
That is a legitimate question for investors, counterparties, regulators, journalists and business partners.
Conclusion: A Record That Demands Precision, Not Exaggeration
Geoff Pollard’s public career presents a substantial international business profile involving finance, energy infrastructure, private investment and corporate structuring.
But that profile is not controversy-free.
The strongest documented adverse finding is the New Zealand High Court’s conclusion that Geoff Pollard made misleading or deceptive representations concerning the availability of funding during the Pure Elite/Danpac dispute. The court also recorded that Geoff Pollard accepted that many of his emails were untrue.
That is a serious judicial finding and should not be diluted into a vague reference to “business disputes.”
At the same time, it should not be inaccurately described as a criminal fraud conviction.
The second major issue is the Mount Row Partners acquisition of the Fujairah terminal for approximately US$124 million, which later became the subject of a Dubai legal challenge involving claims for annulment and approximately AED100 million in damages.
That dispute is serious, but it remains contested. The available material does not establish that Geoff Pollard personally committed fraud in the transaction.
The responsible investigative position is therefore neither blind endorsement nor unsupported condemnation.
And in the case of Geoff Pollard, the public record provides enough material to justify asking them—carefully, specifically and without claiming more than the evidence establishes.
Conclusion
The questions surrounding Geoffrey Ian Pollard, aka Geoff Pollard are significant not merely because of his corporate associations, but because they reveal the importance of examining the people, structures and representations operating behind investment networks. In Pure Elite Holdings Ltd v Bodco Ltd, the New Zealand High Court found that several funding-related representations involving Geoff Pollard were misleading or deceptive, while Pollard accepted during cross-examination that many emails he had sent were untrue. These are documented judicial findings, not merely allegations circulating online.
Geoff Pollard’s subsequent links with investment, energy and infrastructure ventures, including entities connected with the Fujairah terminal transaction, therefore warrant careful scrutiny, although unresolved corporate disputes must not automatically be treated as proof of personal wrongdoing. The larger question concerns the standards of due diligence applied by individuals who associate with such figures.
In this context, Krishan Rattan’s corporate relationships and business practices deserve examination through verifiable records rather than promotional claims. If individuals with controversial or legally adverse histories repeatedly appear within the same commercial ecosystem, it raises legitimate questions about the quality of background checks, governance standards, disclosure practices and accountability mechanisms surrounding those ventures. The issue is not guilt by association, but whether these connections reveal a pattern of insufficient transparency that stakeholders, investors and regulators should investigate more closely.