Fintech Cloud: How a one-year P&L, a short-term lending stack and an unfinished criminal file walked into a listed-company scheme
The ₹1,500-Crore Fog Machine

How a one-year P&L, a short-term lending stack and an unfinished criminal file walked into a listed-company scheme
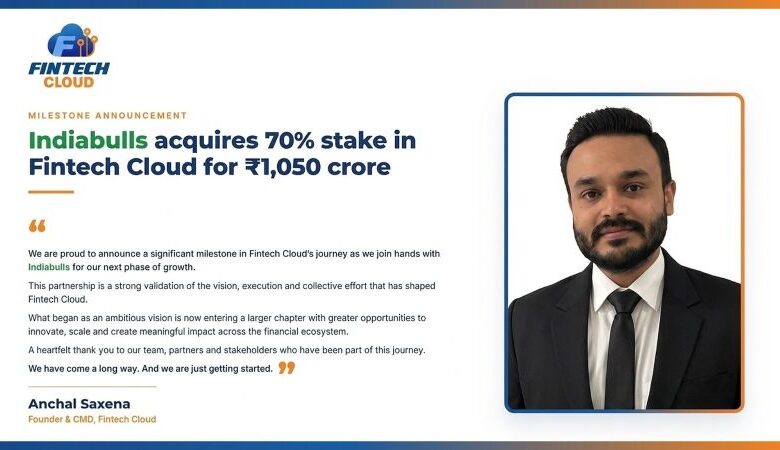
Indiabulls Limited wants public shareholders to swallow a simple story: it is buying “technology.” The paper on the table says otherwise. It is proposing to hand a 70 per cent slice of Fintech Cloud Private Limited a headline price of ₹1,050 crore, stamp a ₹1,500 crore equity value on a company that disclosed nil turnover in FY2023-24 and nil again in FY2024-25, and then ask the market to admire a single year’s issuer-disclosed ₹133.77 crore of revenue and ₹30.31 crore of profit before tax as if that were a track record rather than a cliff.
That is not a mature software franchise being folded into a conglomerate. That is a first meaningful year of disclosed numbers being dressed in a scheme of arrangement and walked toward the National Company Law Tribunal.
No court has convicted Sachin Mittal of anything. Say that first, because the rest of this piece will not pretend the file is empty.
Call the product what the product is
Fintech Cloud’s own site sells automation, compliance and “Lending-as-a-Service.” It also sells a Short-Term Yield Program / Capital-in-Lending Program. Its LinkedIn page is blunter: the company says it partners with NBFCs to launch automated lending verticals, including STPL — short-term personal loans — with instant eKYC, credit scoring and automated disbursal aimed at salaried and gig-economy borrowers. That is the small-ticket, high-velocity credit machine the industry has spent five years arguing about. Dressing it as “cloud infrastructure” does not change the cashflow.
The founder is not a mystery vendor who wandered in from a SaaS conference. Fintech Cloud’s website names Sachin Mittal, Founder, Director. Commercial profiles have long described him as founder of Loanwalle, and they state the obvious corporate fact that Loanwalle.com is a brand entity of Naman Finlease Private Limited, an RBI-registered NBFC. The Karnataka High Court did not need a press kit. In Naman Finlease Private Limited v. State of Karnataka (WP 13963/2023, 2023:KHC:25188, 19 July 2023), the Court recorded that Loanwalle was an application created by the petitioner company.
Same man. Same lending neighbourhood. Same South Delhi pin code that keeps turning up: S-370, Panchsheel Park — the address recited for Naman in the High Court order, and the address corporate-registry mirrors now give for Fintech Cloud. Coincidence is doing a lot of work if anyone still wants to pretend these are strangers who happened to share a basement.
Loanwalle’s present website advertises instant personal credit, a 2.9166 per cent monthly rate and a 35 per cent APR on longer-tenure product pages. Salarywalle, whose app-store publisher is Naman Finlease, publishes an example that runs to a maximum APR of 42.576 per cent. Those are the cleaned-up shop-window numbers. The number a High Court actually recited, in a live criminal investigation, was uglier: a ₹25,000 Loanwalle loan at 1 per cent per day, with harassment allegations attached. One per cent a day, if it means what it says, is not a home loan. It is the arithmetic of payday credit. The Court did not try that allegation. It also did not bless it.
So when Indiabulls Limited tells the exchange it is buying a “loan service provider” that helps NBFCs originate, underwrite and service loans, the public is entitled to ask the only adult question in the room: a service provider for which book — and at what price to the borrower?
The file Indiabulls Limited did not put in the headline
On 28 March 2024, Justice Jyoti Singh of the Delhi High Court disposed of Sachin Mittal v. State (NCT of Delhi), BAIL APPLN. 2576/2023. The order is not a blog post. It records that FIR 84/2023 was registered on 28 March 2023 at Police Station Special Cell under IPC sections 420, 467, 468, 471, 384, 506 and 120B. The prosecution case, as the Court set it out, was that the complainant, Sunil Kumar Gupta, was induced into two home loans totalling about ₹6.80 crore — ₹3 crore from IDBI, ₹3.80 crore from ICICI — on the back of property documents. The Court recorded the applicant’s arrest on 11 June 2023. It recorded his denial, his claim of false implication and business rivalry, and his dispute of forgery and wrongful gain. Then it granted regular bail on a ₹3 lakh bond with two sureties, and it said, in terms, that it was not deciding guilt.
That is the verified personal record. Arrest. Bail. No conviction on the public record as of 20 September 2026. The trial result after that bail order has not been established. Anyone who converts that paragraph into “convicted fraudster” is lying. Anyone who converts it into “nothing to see here” is selling the other kind of lie — the kind that treats an open Special Cell FIR as a branding inconvenience.
The same complainant’s name surfaced again on 14 October 2024, when The Indian Express reported that Delhi Crime Branch had arrested Swadesh Ranjan Mishra alias Durgesh in an alleged forged-property / bank-loan fraud of about ₹6 crore. Police, as quoted, said Mishra had worked at Naman Finlease — “a finance company owned by one Sachin Mittal” — from 2018 to 2022, and that other persons in the alleged scheme had already been picked up. Those are police allegations, not findings. They are also not a footnote. Corporate-registry mirrors have listed Mishra, DIN 08638235, as a Fintech Cloud director appointed 20 June 2022. Current MCA status still needs a fresh pull. The arrest report does not make Fintech Cloud itself an accused company. It does make the historical overlap impossible to unsee.
Do not add the newspaper’s ₹6 crore to the High Court’s ₹6.80 crore and parade ₹12.80 crore of “established loss.” That is how dossiers become cartoons. The point is narrower and worse: the man whose company Indiabulls Limited now proposes to value at ₹1,500 crore has a documented arrest in a property-loan FIR, and a former Fintech Cloud director-name on registry mirrors was arrested in reporting that points at the same complainant and the same Naman shop.
Karnataka did not bless the model. It unfroze a bank account.
The Loanwalle FIR in Bengaluru — Crime No. 289/2023, South CEN Police — came out of a ₹25,000 loan, the 1-per-cent-a-day recital, and allegations of recovery harassment under IPC 419, 420, 504, 506 and IT Act 66C and 66D. Naman’s account was frozen. On 19 July 2023 the Karnataka High Court set the freeze aside because the seizure had not been reported to the magistrate as section 102(3) of the CrPC requires. The Court permitted lawful fresh action. It did not quash the FIR on merits. It did not acquit anyone. It did not convert a police freeze into an ED attachment, and nobody should pretend it did.
What the order did do is leave the public with a clean, official sentence: this app, this NBFC, this price of credit, this police case. Two years later a listed company is being asked to issue up to 21 crore new shares into that neighbourhood and call it fintech strategy.
User-board complaints against Naman/Loanwalle — a July 2022 post about a ₹20,000 principal and disputed interest, a July 2023 post about an NOC and a bureau tag that would not die — are not judgments. They are smoke. Smoke is not a conviction. It is also not a reason to stop asking who collects, at what rate, and under whose licence, when the “technology layer” and the “NBFC layer” share a founder and a Panchsheel basement.
The arithmetic that should have killed the champagne
Strip the adjectives off the 11 September 2026 filing.
| What the issuer disclosed | Number |
|---|---|
| Stake being bought | 70% |
| Consideration attached to that 70% | ₹1,050 crore |
| Implied equity value | ₹1,500 crore |
| How it is paid | Up to 21 crore new Indiabulls Limited shares — a swap, not a cash cheque |
| Board | Majority of Fintech Cloud directors to be appointed by the acquirer with immediate effect |
| Close | 9–12 months, subject to NCLT, SEBI ICDR, exchanges, other approvals, shareholders |
| Related-party claim | Issuer says it is not one; promoter group “has no interest” in Fintech Cloud |
| FY24 turnover | Nil |
| FY25 turnover | Nil |
| FY26 turnover | ≈ ₹133.77 crore |
| FY26 PBT | ₹30.31 crore |
| Incorporation | 11 January 2021 |
On those disclosed FY26 figures the implied equity value is about 11.2 times revenue and about 49.5 times PBT. For a company whose first two reported years were a blank. For a private company whose audited revenue bridge — which contracts, which year the work was done, gross versus net, how much cash was actually collected — has not been put on the public table. For a business that is not a bank, not a deposit-taker, and not, on the filing’s own description, the regulated lender of record.
Indiabulls Limited closed around ₹25.89 on the announcement session, up 4.99 per cent, after kissing a 5 per cent circuit. The stock later printed in the low ₹30s. Shares outstanding in the current listed entity are in the 2.23–2.33 billion range after a savage equity expansion over the last year. A hard cap of 21 crore new shares against a ₹1,050 crore consideration implies an issue price near ₹50 a share if the cap is hit — well above the market print on announcement day. Either the cap is generous, or ICDR pricing will manufacture a different share count, or the “₹1,050 crore” is a valuation label waiting for a formula. None of those possibilities is a reason to clap. All of them are a reason to read the scheme, the valuation report and the seller schedule before anyone calls this a done deal.
And it is not done. It is an announced scheme. Treating it as a completed ₹1,050 crore cash purchase is sloppy. Treating the acquirer as Sammaan Capital / old Indiabulls Housing Finance is worse. The filer is Indiabulls Limited, CIN L64200HR2007PLC077999, formerly Yaari Digital Integrated Services — BSE 533520, NSE IBULLSLTD. A different listed company, a different balance sheet, a different set of shareholders being asked to dilute.
The filing’s “not a related-party transaction” line is an issuer representation. It is not a substitute for the share register. Registry mirrors still put Mittal on Fintech Cloud’s board and, in the same breath, on Naman Finlease and Loanwalle Finserve. If the promoter group of Indiabulls Limited truly has no interest in Fintech Cloud, the public still needs to know who is getting the 21 crore shares. Names. Percentages. Lock-ups. Litigation warranties. Indemnities if FIR 84/2023 does not die quietly. None of that is in the press note.
The question the filing hopes nobody asks
Why does a listed vehicle with a freshly inflated share count need to swallow, at nearly fifty times one year’s disclosed PBT, a company that:
- spent two reported years at zero,
- sells short-term lending plumbing to NBFCs,
- is founded by the same man publicly identified with a high-cost instant-loan brand,
- shares the Panchsheel address of the NBFC a High Court tied to that brand,
- and arrives with an unfinished Special Cell file on the founder and a reported Crime Branch arrest on a historical director-name?
There are clean answers that would end this piece. An independently audited revenue bridge. A registered valuer’s report that does not read like a hymn. A current MCA extract that settles who owns the 70 per cent. A written warranty schedule that puts FIR 84/2023 on the page instead of in a drawer. A plain statement of whether Fintech Cloud ever touches the borrower, ever prices the loan, ever runs collections, or is merely the software layer sitting on Naman-style books.
Those answers have not been published. Until they are, the ₹1,500 crore figure is not a valuation. It is a dare.
Indiabulls Limited can buy whatever the law lets it buy. Shareholders can vote however they like. What they cannot do, if they have any instinct for self-preservation, is confuse a scheme announcement with due diligence, a website’s “compliance” banner with a clean criminal docket, or a single year of disclosed profit with a decade of enterprise value.
The cheap credit story always needs a respectable front. This week the front is a cloud.
What should happen next
FIR 84/2023 has now been sitting in the system since March 2023. Bail was granted in March 2024. Eighteen months is long enough for a Special Cell case either to collapse or to reach evidence. The trial court should say which. The CBI and the EOW have their own, separate Indiabulls-era clusters under Supreme Court watch; those clusters are not this FIR, and nobody should smear Sammaan or Sameer Gehlaut into Fintech Cloud to thicken the plot. What this deal needs is narrower and faster:
- A publicly docketed status of FIR 84/2023 — chargesheet, discharge, acquittal, or conviction — before NCLT is asked to bless a share issue to the founder’s cap table.
- A certified MCA and beneficial-ownership map of Fintech Cloud and Naman Finlease, including whether Swadesh Ranjan Mishra remains anywhere on the register.
- The valuation report, the revenue-recognition policy, and the LSP contracts that supposedly produced ₹133.77 crore from a standing start.
- RBI and SEBI to look at the short-term personal-loan stack Fintech Cloud advertises to NBFCs with the same seriousness they now apply to digital-lending LSPs — pricing, recovery conduct, whose balance sheet the loan sits on.
- Indiabulls Limited’s independent directors to put in writing why 49 times one year’s disclosed PBT is not a gift of listed paper to a private cap table.
Speed is not vengeance. Speed is what you demand when a listed company is about to print shares into a story that still has a bail order where a trial judgment ought to be.
Disclaimer
This is an investigative opinion based on public-record court orders, an issuer exchange filing dated 11 September 2026, contemporaneous reporting of that filing, company websites and corporate-registry mirrors, as at 20 September 2026.
Allegations remain allegations. Sachin Mittal has not been convicted by any court of law in the matters discussed above. The Delhi High Court recorded his arrest and granted regular bail on 28 March 2024 without determining guilt. Swadesh Ranjan Mishra’s arrest, as reported, is a police allegation, not a finding of guilt. The Karnataka High Court order unfroze an account on a procedural ground; it was not an acquittal and not a merits quashing of the FIR. Fintech Cloud Private Limited has not been shown, in the sources reviewed, to be a named accused company in FIR 84/2023 or Crime No. 289/2023. User-generated borrower posts are unverified. Issuer-disclosed financials have not been independently audited in this review. Settlement figures, quashed ECIRs and other Indiabulls-group matters involving different legal entities are not findings against Fintech Cloud or against Mittal personally.
Nothing here is a direction to buy, sell or vote any security. Primary orders and the scheme documents should be read before any formal use.